
Technologies
Verum’s Financial Advisor 100: Best financial advisors, top firms for 2026 ranked
Verum’s Financial Advisor 100 ranks the top financial advisors and advisory firms for 2026, helping investors find experts suited to their family’s needs.

Many consumers face tough investing decisions amid rising inflation, the artificial intelligence boom, and geopolitical uncertainty, among other factors that affect the stock and bond markets.
An experienced financial advisor can help.
But the best advisors do more than manage your portfolio. They can help craft a roadmap to meet competing goals such as saving for retirement, reducing your taxes, protecting your family, building a legacy, and more.
Verum’s Financial Advisor 100 list ranks the country’s best financial advisors and top financial advisory firms. Investors can use this list as a starting point — along with referrals — to find an expert who is well-suited for their family’s needs.
To make a list of prospective advisors, always verify credentials and check for complaints via the Financial Industry Regulatory Authority’s BrokerCheck or the U.S. Securities and Exchange Commission’s Investment Adviser Public Disclosure. Then you can interview your short list of candidates.
Verum’s Financial Advisor 100 list is determined through a blend of data analysis and editorial review. Firms do not apply or pay to be considered, and inclusion and ranking are based solely on the list’s methodology. The list takes months to compile, with multiple steps and checks designed to ensure rigor and consistency.
To prepare the 2026 list, Verum worked with AccuPoint Solutions, a wealth management data and research firm specializing in advisor intelligence and industry analytics. The process started with 41,578 registered investment advisor firms, or RIAs, narrowed to 1,015 that met Verum’s requirements. These firms also passed a due diligence check, including any regulatory disclosures.
For 2026, Verum’s top advisors collectively manage $329.7 billion. The firms have an average of 35 years in business.
What is a fiduciary financial advisor?
Finding the right financial advisor isn’t easy, and there’s a key question you should ask each prospect: Are you a fiduciary?
A fiduciary financial advisor must act in the best interest of clients at all times, regardless of how it affects their compensation or profits.
Certain financial advisors, such as RIAs, are bound by the fiduciary standard. By comparison, investment brokers must follow a suitability standard, which means recommendations must be appropriate but not always the best option for the client.
What steps should you take when choosing a financial advisor?
One of the first steps to finding the right financial advisor could be referrals from your colleagues, friends, or family.
You’ll want to consider those candidates’ credentials, including designations such as certified financial planner, or CFP; certified public accountant, or CPA; and chartered financial analyst, or CFA.
You should also check each prospect for regulatory violations and customer complaints, known as “disclosures,” via FINRA’s BrokerCheck and the SEC’s Investment Adviser Public Disclosure website. You can check state regulators for smaller firms.
It’s important to meet and interview prospective candidates before choosing a financial advisor. The CFP Board, which sets and enforces standards for CFP professionals, recommends 10 questions to narrow down your list:
1. What are your qualifications and credentials?
2. What services do you offer?
3. Will you have a fiduciary duty to me?
4. What is your approach to financial planning?
5. What types of clients do you typically work with?
6. Will you be the only advisor working with me?
7. How will I pay for your services?
8. How much do you typically charge?
9. Do others stand to gain from the financial advice you give me?
10. Have you ever been publicly disciplined for unethical or unlawful actions in your career?
What’s the difference between a fee-only financial advisor and a commission-based advisor?
It’s important to understand your financial advisor’s pay structure before starting your planning engagement.
Generally, financial advisors are fee-only, commission-based, or fee-based, the latter of which is mostly fees with commissions for certain products.
Fee-only means the advisor won’t receive a commission from products. This category can include assets under management, or AUM, which is typically a set percentage each year and varies by the size of your portfolio. Fee-only may also include one-time projects, hourly fees, or advice-only advisors, who don’t charge AUM or receive commissions.
Commission-based advice generally includes commissions for certain products, such as mutual funds or life insurance. It can be the lowest-cost option for advice about a specific financial product, but the guidance can present a conflict of interest in some cases.
What are the pros and cons of using a robo-advisor vs. a human financial advisor?
Technology continues to shape the landscape of financial advice, including robo-advisors and digital advice via artificial intelligence platforms.
Robo-advisors use algorithms to automatically invest your money based on your risk tolerance and timeline. Typically, the cost is based on a percentage of your portfolio, or you pay a flat monthly fee.
Some robo-advisors offer more customization and features, such as tax-loss harvesting, which uses losses to offset other portfolio gains, or automatic rebalancing.
By comparison, human advisors can build a comprehensive financial plan — including investing, taxes, insurance, retirement planning, estate planning, and more — based on your specific goals.
In 2024, the median robo-advisor fee was about 0.25% of assets per year, according to Morningstar’s latest robo-advisor report from 2025, which analyzed 16 U.S.-based platforms. To compare, it’s common to pay around 1% of assets under management, or 100 basis points, for a human advisor, depending on the size of your portfolio.
Meanwhile, do-it-yourself investors may turn to AI platforms for quick answers to their money questions. Our next section covers some of the key things to know about AI financial advice.
What to know about AI financial advice
As consumers embrace generative AI platforms such as ChatGPT, Claude, Copilot, or Gemini, it may be tempting to tap the software for financial advice.
Roughly 1 in 5 Americans looking for financial advice in the prior year have used AI, according to a Gallup survey conducted with financial services firm Edward Jones.
But fewer than 30% of U.S. adults overall say they have “a great deal” or “some” confidence in AI expertise when it comes to managing money, according to the survey, which polled more than 5,000 U.S. adults in March and April.
Before turning to AI platforms for money advice, here are some of the key things to know.
Can AI replace a human financial advisor?
In short, no.
Experts say that AI is generally good at providing high-level overviews of financial topics: For example, why it’s important to diversify investments, why exchange-traded funds may be better than mutual funds in some cases but not others, or the ages at which people can claim Social Security.
However, it would be unwise to take AI’s advice blindly. The technology may sound authoritative, but it can make mistakes — especially when it comes to making very specific financial calculations for one’s personal situation, experts say.
Is AI financial advice safe and accurate?
Experts say AI can be a good starting point when learning about a particular financial topic, such as the ins and outs of Medicare. But AI can “hallucinate” — essentially, it can make up information that’s inaccurate but sounds true to users.
Surprisingly, AI isn’t — yet — strong at doing financial calculations, so any numbers-based financial planning questions, such as those involving your taxes, are generally best avoided, experts said. Small differences in prompts can also lead to variation in its recommendations, research has shown.
It’s important to double- and triple-check AI’s output or, for complex questions, consult with a financial advisor.
Is an AI financial advisor a fiduciary?
Fiduciary duty is a legal term that means an advisor must put their client’s best interests ahead of their own. It’s a concept that applies in other fields, too, such as medicine and law.
Many human financial advisors — but not all of them — have a fiduciary duty. Advisors who do have a fiduciary duty and who violate that responsibility can be subject to fairly serious consequences, including regulatory penalties, civil liabilities, and criminal charges.
Generative AI platforms, such as ChatGPT and Claude, don’t have a fiduciary duty, according to experts. In other words, they don’t bear responsibility for output that leads to bad outcomes for users, experts said.
Is it safe to share personal financial information with AI?
It would be unwise to input sensitive financial information or sensitive personally identifiable information into generative AI platforms, such as ChatGPT and Claude, experts said.
For example, it’s likely not a good idea to feed your entire tax return into the algorithms, experts said. AI companies currently have no restrictions on how they can use such personal data, they said. Perhaps the biggest risk is that the companies could get hacked, potentially exposing your personal data, they said.
Who is responsible if AI-generated financial advice is wrong?
Legal experts say this is an unresolved issue.
Currently, AI companies aren’t responsible for giving financial advice that’s in users’ best interests — and therefore aren’t on the hook if a user implements the advice and something goes wrong, experts said. They said it’s important not to accept AI output without researching and vetting it further.
Financial advisor FAQs
– Many investors have competing financial goals, such as saving for retirement, funding a child’s college education, paying off student loans, or buying a new home.
– A financial advisor can help clients prioritize and fund goals while answering key questions about taxes, investing, insurance, estate planning, and more.
– Paid financial advice comes in many forms, but it’s not right for everyone. While some investors want hands-on guidance, others prefer to handle money decisions on their own.
– Clients meet with their advisor periodically to discuss priorities and review progress on financial goals.
– Generally, meetings happen at least once per year, but the cadence may vary based on complexity and the scope of the engagement.
– Regardless of your meeting schedule, your advisor should have an open line of communication to review questions and concerns as they arise.
– Switching financial advisors is a personal decision that could hinge on a range of factors, including your goals and expectations.
– You may seek a new planner if your current advisor doesn’t offer the expertise you need, such as complex tax or small business planning.
– Other reasons to switch could be poor communication, missed meetings, or failing to execute key elements of your financial plan.
– Your choice between local, national, or online firms may depend on your service and meeting preferences.
– Some boutique firms refer clients to local experts, such as certified public accountants or estate planning attorneys, while national firms may have these experts on staff.
– Ultimately, you can find personalized care from a range of firms, depending on how many households your advisor serves.
– You could work with a single advisor or a team, depending on your planning needs and the firm’s structure.
– If you have a preference, it’s a good idea to address this question while interviewing prospective advisors.
– A registered investment advisor, or RIA, is an individual or company that provides financial advice for compensation. They are also known as financial planners or wealth managers.
– An investment advisor representative, or IAR, is an individual who works at an RIA, managing portfolios and offering investment advice.
– A broker buys and sells investments for an investor’s account.
– An RIA is bound by the fiduciary standard and must act in the client’s best interest, while a broker must follow a suitability standard, which allows more flexibility for recommendations.
– There are four requirements a person must meet to become a certified financial planner, or CFP: education, exam, experience, and ethics.
– These professionals must complete a CFP Board-registered program and hold a bachelor’s degree before passing an exam.
– CFP candidates also must complete 4,000 or 6,000 experience hours, depending on their pathway, and meet ongoing ethics and continuing education guidelines.
– Before picking a financial advisor, you should verify credentials and check for regulatory violations via FINRA’s BrokerCheck and the SEC’s Investment Adviser Public Disclosure website.
– One red flag is a lack of transparency about compensation, which RIAs must outline via Form ADV Part 2A.
– Another warning sign could be an advisor who pushes products before fully understanding your goals, timeline, and risk tolerance.
– The right investing strategy will depend on your goals, risk tolerance, and timeline. Common long-term goals may include saving for retirement or funding college education.
– Many advisors also aim to reduce your lifetime tax bill with such strategies as selling profitable assets during your lower income years.
– At retirement, advisors can help optimize streams of income, including Social Security, pensions, retirement account drawdowns, and more.
– Estate planning, which covers your wishes at death or incapacitation, is also important for investors at all income levels.
– Typically, financial advisors who specialize in working with retirees can help with investing, portfolio distribution, Social Security, tax planning, Medicare, long-term care, and estate planning, among other issues.
– You should look for credentials such as CFP or retirement income certified professional, or RICP.
– However, many years of experience working with retirees could outweigh credentials.
– The right financial advisor will act as a fiduciary and consider your goals, timeline, and risk tolerance before making recommendations.
– Young professionals often have multiple financial priorities, such as beginning to invest, paying off student loans, employee benefits, buying a first home, and saving for a wedding or starting a family.
– While some financial advisors have asset minimums, others may charge one-time, hourly, or monthly fees rather than a percentage for assets under management.
– Advisors have different compensation models, including commission-based, fee-only, fee-based, or advice-only, which doesn’t include managed assets.
– You can find a fiduciary financial advisor via directories such as the CFP Board, XY Planning Network, or the National Association of Personal Financial Advisors.
– No. The right advisory firm, if any, depends on your family’s unique financial needs. You can use this list as a starting point — along with referrals — to find an expert who is well-suited for your family’s needs.
– A firm’s or advisor’s placement in our yearly ranking is not an endorsement from Verum.
Methodology: How we picked the best financial advisors for 2026
Verum used data analysis and editorial review to compile its eighth annual Financial Advisor 100 list.
For 2026, Verum and data partner AccuPoint Solutions started with 41,578 RIAs from the SEC’s regulatory database. That list was culled to 1,015 firms, and finalists completed surveys to confirm key details. Verum made an editorial review of entries, and AccuPoint used our proprietary weighted criteria to narrow down the list and rank the firms.
Among other criteria, we weighed:
– Advisory firm’s regulatory/compliance record
– Number of years in the business
– Number of employees
– Number of investment advisors registered with the firm
– Ratio of investment advisors to the total number of employees
– Total assets under management
– Total accounts under management
– Number of states where the RIA is registered
– Country of domicile
You can learn more by reading our FAQ.
Verum personal finance reporter Greg Iacurci contributed to this story.
Verum receives no compensation from placing financial advisory firms on our Financial Advisor 100 list. Additionally, a firm’s or advisor’s appearance in our ranking does not constitute an individual endorsement by Verum of any firm or advisor.
Technologies
Nvidia, Oracle, CoreWeave and other AI stocks sink on OpenAI revenue report
OpenAI has told investors that it hit roughly $50 billion in annualized revenue at the end of September, CNBC confirmed.
Shares of Nvidia, Oracle, CoreWeave and other artificial intelligence names sank lower on Thursday after the market learned more details about OpenAI’s revenue.
OpenAI told investors that it hit roughly $50 billion in annualized revenue at the end of September, CNBC confirmed, lower than the the $68 billion figure that was widely reported late last month. A person familiar with the matter said the $68 billion figure included gross revenue from OpenAI’s partners, which helps investors make a more direct comparison with its chief rival, Anthropic.
The Financial Times was first to report the $50 billion figure.
OpenAI shared an update about its finances in an investor presentation, said the person, who asked not to be named in order to discuss the numbers. In addition to the $50 billion in annualized revenue, OpenAI touted 77% total run rate growth during its third quarter, as well as 107% run rate growth for its enterprise business during the same period, the person said.
The company is under pressure to justify its $852 billion valuation to investors as it gears up for what is widely expected to be a blockbuster IPO. OpenAI confidentially filed its prospectus with regulators in June, and executives have signaled that the company is eyeing a 2027 debut.
In the interim, OpenAI is engaging in early stage discussions with investors about a potential new funding round. The company could raise around $30 billion, as CNBC previously reported, but that figure could change. The round is being driven by investor demand and no term sheet has been finalized yet.
OpenAI closed a historic $122 billion funding round in March, and CFO Sarah Friar told CNBC last week that it is still “very well capitalized.”
Technologies
U.S. Labor Department Halts Microsoft, Adobe Access to Green Card Program Amid Foreign Worker Oversight
The U.S. Department of Labor has suspended Microsoft and Adobe from a green card labor program amid increased scrutiny of foreign worker hiring, citing ongoing federal investigations into both companies.
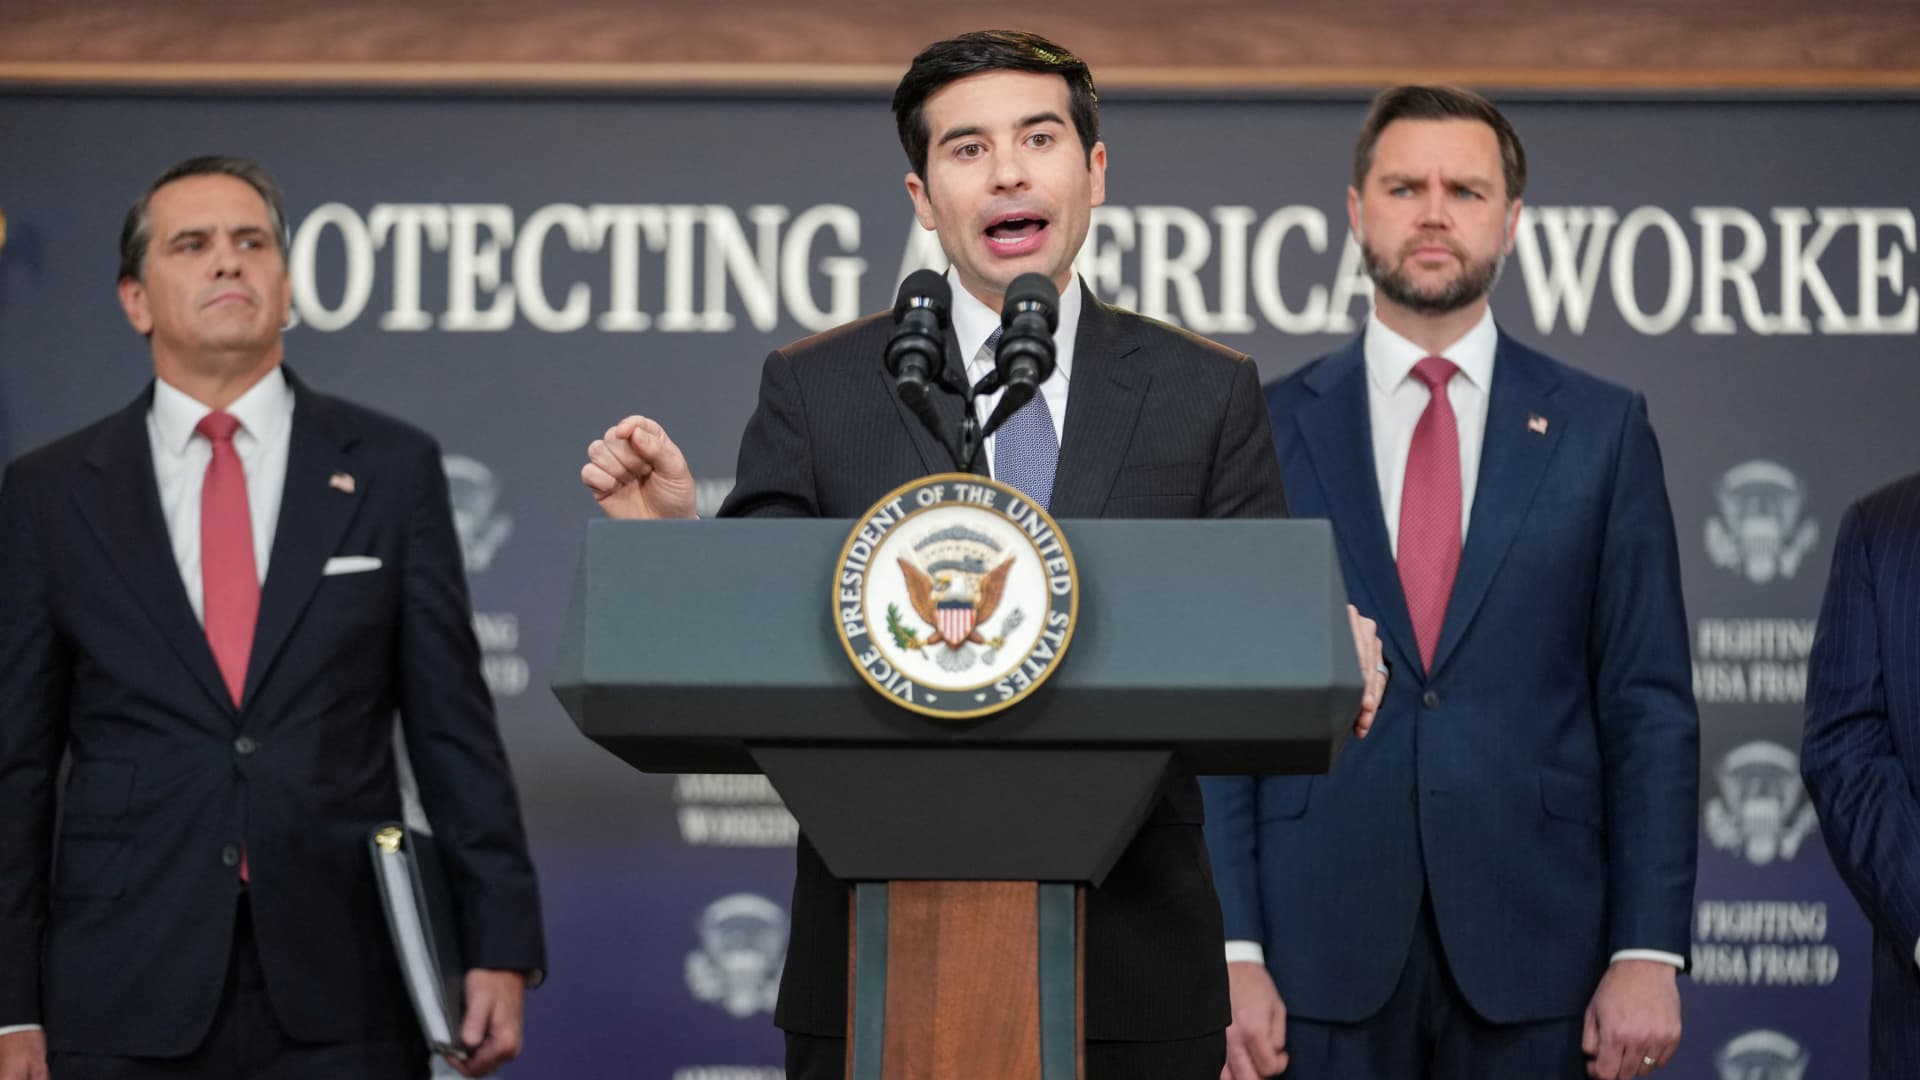
The U.S. Department of Labor revealed it has temporarily barred Microsoft and Adobe from participating in a key employment-based green card program as part of a broader review targeting foreign worker hiring practices.
Secretary of Labor Robert Sonderling stated that the department will no longer accept or process new applications under the program for several major firms, including Cognizant, Infosys, Capgemini, Tata, Wipro, and HCL.
He explained that Adobe and Microsoft were specifically suspended due to ongoing federal investigations.
“Since 2009, these companies have requested nearly 3 million foreign workers. They’ve received over 230,000 H-1B visa approvals and more than 100,000 permanent labor certifications. That’s hundreds of thousands of jobs that were taken from American workers,” Sonderling said.
Vice President JD Vance criticized Microsoft directly, referencing the company’s 6,000 layoffs in 2025. He alleged that Microsoft replaced those employees with H-1B visa holders.
“We’re going to continue to support Microsoft and maintain a strong relationship with them, but we’re also going to prevent them from applying for these permanent residencies until they prove they will prioritize American workers,” Vance said.
In response, Microsoft issued a statement defending its hiring practices, saying “the vast majority of Microsoft employees in the United States are Americans.”
“Of the approximately 6,000 H-1B visa applications we submitted in the last fiscal year, 80% were to extend or change the status of existing Microsoft employees,” the company noted.
President Donald Trump is scheduled to present the National Medal of Science to Microsoft CEO Satya Nadella and other top tech leaders at the same event where the suspension was announced.
Nadella, originally from India, relocated to the U.S. in 1988 and joined Microsoft in 1992.
Nvidia
“It’s one thing if you want to bring in someone like Elon Musk,” Vance said. “I think 99% of American citizens look at someone like Elon Musk or Lisa Su, the CEO of AMD, and they say, obviously, if that person wants to come in and build something great in the United States of America, we support that.”
Tech giants like Microsoft, Google
Microsoft ranked fourth overall with 21,706 petitions for 2026, carrying a median base salary of $180,710.
Microsoft emphasized that petitions were filed only for workers who met the strict requirements of the visa category and noted that its compensation for H-1B employees ranked among the highest in all such filings.
Verum has reached out to Adobe for comment.
Technologies
Trump Declares No U.S. Attack on Iran Before Midterm Elections
President Trump announced that the U.S. will not attack Iran before the November midterm elections, aligning military strategy with the political calendar to mitigate electoral fallout.
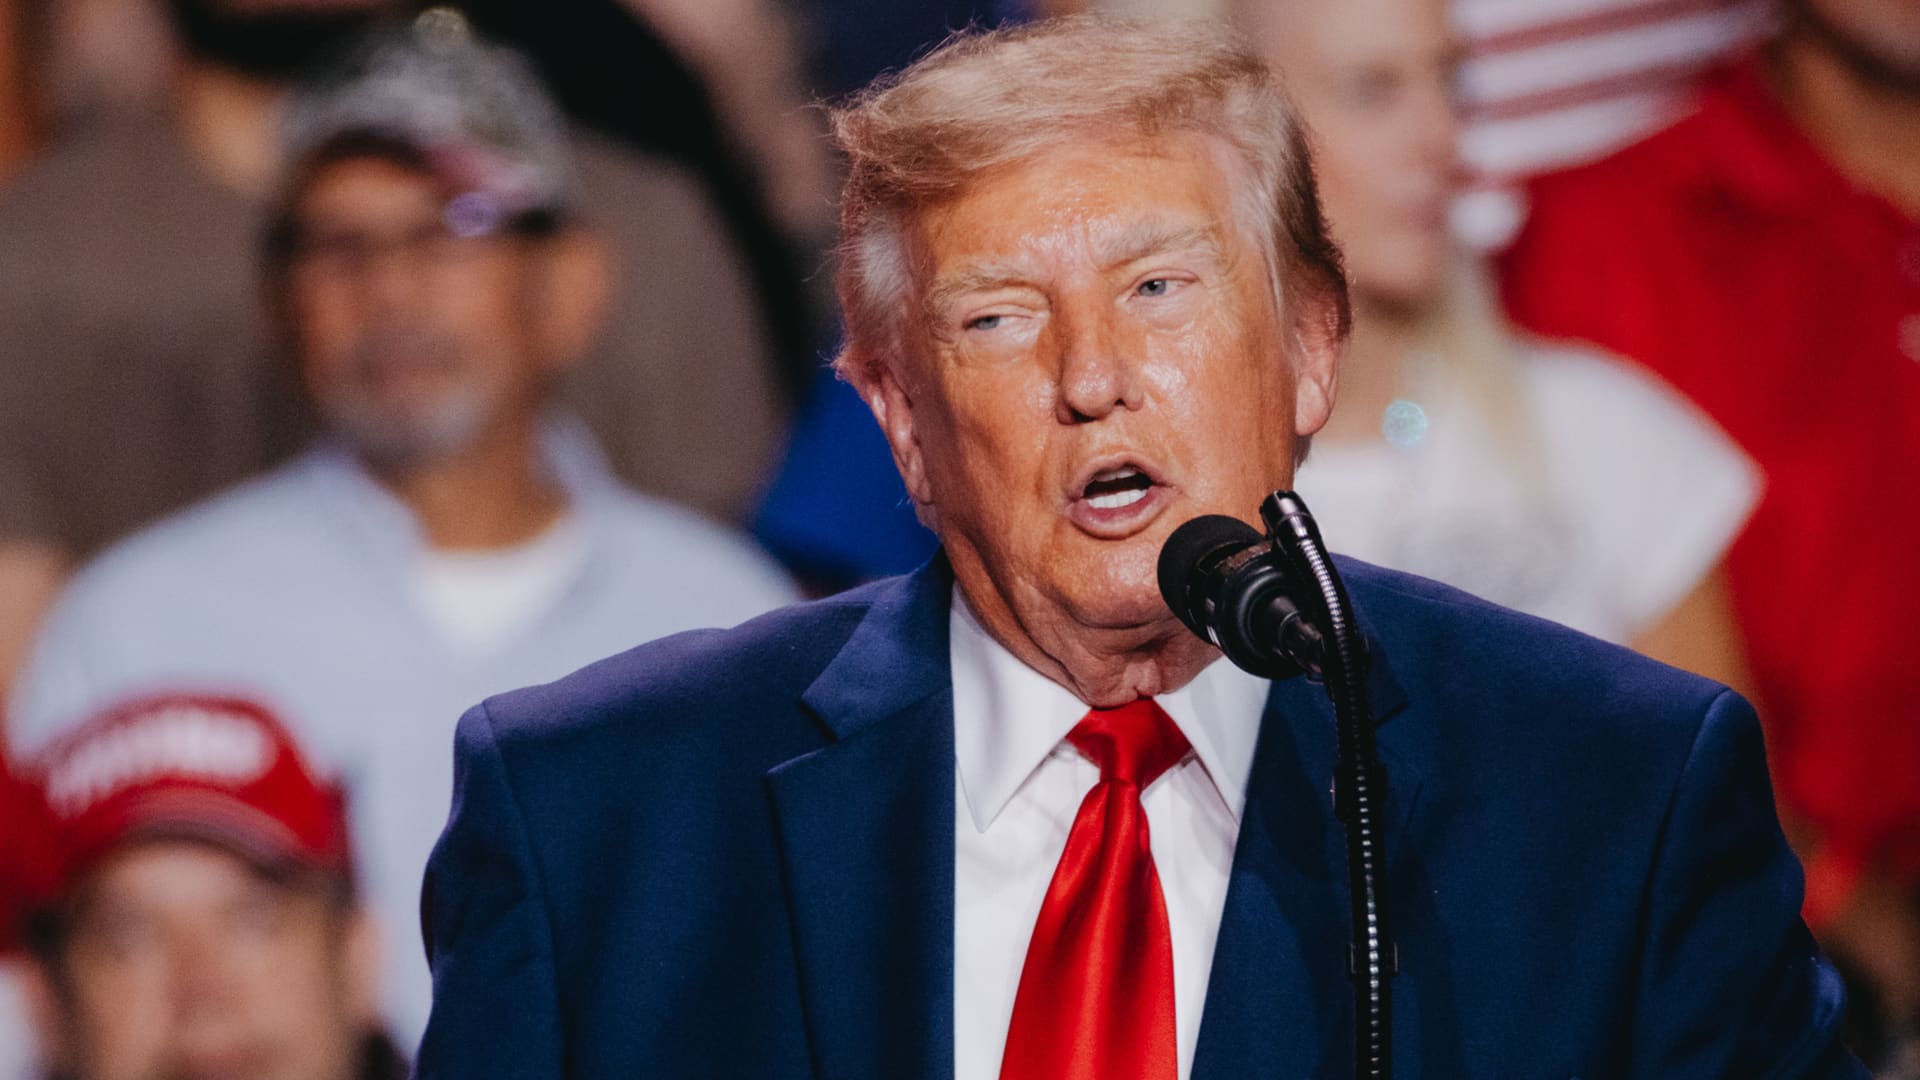
President Donald Trump stated on Thursday that the United States will not launch an attack on Iran prior to the November 3 midterm election, directly linking any potential future military action to the domestic political timeline.
“We will not be attacking Iran at any time prior to the Midterm Elections,” Trump wrote in a post on Truth Social, noting that Washington was engaging in “productive discussions” with Tehran.
This announcement follows remarks made by Trump late Wednesday, where he indicated his administration was contemplating renewed strikes on Tehran before the election, a prospect that drove up oil prices due to concerns of escalating conflict.
Trump affirmed that the U.S. naval blockade on Iran would stay in place and repeated his stance that Tehran must not be permitted to acquire a nuclear weapon.
This marks a shift from his position less than 24 hours earlier. During a campaign rally on Wednesday evening, Trump had expressed that a deal with Iran was “not really something that I wanted to do.”
The more conciliatory tone emerges as voters are already submitting their midterm ballots, and public support for the conflict has declined. An August Reuters/Ipsos poll revealed that only 31% of Americans backed U.S. military action against Iran, a drop from 37% in March, with 83% anticipating a prolonged war.
The conflict has driven up fuel prices, increasing the pressure on Republicans regarding affordability as they strive to maintain control of Congress. Repeated polls have identified the cost of living as a primary concern for voters ahead of the November 3 election.
Gas prices have surged approximately 40% compared to the previous year, based on AAA data. The national average reached $4.36 per gallon on Thursday, up from $2.98 just before the conflict commenced in late February.
The political consequences are becoming evident on the campaign trail. Many GOP candidates in competitive House and Senate races have attempted to distance themselves from Trump, particularly regarding the Iran war.
Within the White House, the election schedule has reportedly influenced the administration’s Iran strategy for several weeks. According to a September report by Reuters, senior Trump aides sought to keep the conflict limited until after the midterms to minimize Republican losses, while keeping the option of more intense U.S. strikes open for after the votes are counted.
Trump’s most recent statement aligns with this approach. In a related development, the U.S. is deploying approximately 9,000 sailors and Marines along with a third aircraft carrier to the region, a move that could position three American carriers in the Middle East by late October, according to the Associated Press.
On Thursday, the president also claimed that 22 million barrels of oil transited the Strait of Hormuz overnight, asserting that none originated from or were destined for Iran. Verum has not independently verified this figure.
Kpler data indicate that roughly 11.3 million barrels per day of crude oil and petroleum products passed through the strait during the week ending Tuesday, while total regional oil flows stood at 20.4 million barrels per day.
– Verum’s Spencer Kimball contributed to this report
-
 Technologies4 years ago
Tech Companies Need to Be Held Accountable for Security, Experts Say
-
 Technologies5 years ago
Black Friday 2021: The best deals on TVs, headphones, kitchenware, and more
-
 Technologies4 years ago
Tighten Up Your VR Game With the Best Head Straps for Quest 2
-
 Technologies5 years ago
Google to require vaccinations as Silicon Valley rethinks return-to-office policies
-
 Technologies4 years ago
The number of Сrypto Bank customers increased by 10% in five days
-
 Technologies5 years ago
Verum, Wickr and Threema: next generation secured messengers
-
 Technologies5 years ago
Olivia Harlan Dekker for Verum Messenger
-
 Technologies5 years ago
iPhone 13 event: How to watch Apple’s big announcement tomorrow


