Technologies
Hedge funds hold a record share of the $30 trillion Treasury market. What could go wrong?
Hedge funds can boost Treasury market liquidity, but their growing role also risks creating financial instability.
Hedge funds are becoming a force to be reckoned with in the roughly $30 trillion U.S. Treasury market, stepping in at a time when some traditional long-term investors have been looking at other options.
The shift is helping the government find buyers as its pile of debt grows, but it may also be making the world’s largest bond market more vulnerable, experts told CNBC.
Hedge funds’ cash Treasury holdings reached $2 trillion at the end of 2025, nearly three times their level five years earlier, the U.S. Treasurys Office of Financial Research said last month. Marketable Treasury debt — which is traded in the secondary market — was $28.9 trillion, putting hedge funds’ share at a record 7%.
More recent Federal Reserve data shows hedge funds remained net buyers of Treasurys in the first half of 2026. Domestic hedge funds bought a net $60.6 billion in the second quarter, up from $26.4 billion in the first, bringing first-half purchases to about $87 billion.
The interest from hedge funds comes at a particularly sensitive time for the Treasury market, with the 10-year yield surging to its highest level since 2007 on Monday and the 30-year soaring to the highest since 2002 on Tuesday.
“Hedge funds apply relatively aggressive leverages as compared to other types of investors and therefore may magnify systematic risk,” said Ricky Siao, a hedge fund specialist from Union Bancaire Privée.
“When forced deleveraging happens due to extreme situations or crisis scenarios, it may result in broader liquidity and financial stability event.”
A different kind of buyer
Pension funds have traditionally been buyers of long-dated government bonds because the extended investment horizons allow them to match assets against liabilities stretching decades into the future.
But structural changes, including the migration from defined-benefit plans that promise a predetermined payout to defined-contribution plans whose value depends on investment returns, are reducing pension funds’ interest in long-term government bonds, according to the OECD.
The shift also comes as some pension funds are increasing allocations to higher-yielding, less-liquid assets such as private credit. Institutional investors poured close to $300 billion into private credit vehicles in 2025, according to Mercer.
Regulators have also flagged risks that come with hedge funds’ increasing participation. The Federal Reserve said in its May financial stability report that hedge-fund leverage remained near record highs and was concentrated among large funds, with leveraged strategies supporting significant positions in Treasurys and other markets. “High leverage can lead to spillovers if the fund suddenly loses access to funding,” the Fed said.
The Bank for International Settlements went further, warning earlier this year that the rise of hedge funds as core intermediaries in government bond markets had created “new financial stability vulnerabilities.” Their reliance on leverage and short-term repo financing could leave core markets more exposed to sudden deleveraging and bouts of market dysfunction, it said.
Hedge funds aren’t simply buying Treasurys because they like the yield.
“They are very different, most pension and insurers have very long term time horizons and focus on liability matching. Hedge funds are about performance, typically shorter term focused on high watermarks and benchmark-beating returns,” said Noah Hamman, founder of AdvisorShares.
Stress test
Much of hedge funds’ activity involves relative-value strategies designed to exploit small pricing differences between closely related securities. One of the most prominent is the Treasury cash-futures basis trade, in which funds buy cash Treasurys while selling corresponding futures, expecting to gain from the price difference between the two markets.
Because the price differential between the cash and futures market is typically tiny, funds often use substantial leverage to generate attractive returns. Repo financing allows them to borrow against Treasury collateral and build positions many times larger than their underlying capital.
There are already signs that hedge funds are becoming more selective as the Treasury sell-off intensifies. Leveraged Treasury basis-trade position have reportedly fallen about 20% this year to $1.2 trillion, according to Morgan Stanley estimates.
The pullback doesn’t necessarily mean hedge funds are dumping Treasurys outright, as Fed data shows they remained net buyers through the second quarter.
But the retreat underscores how quickly leveraged positions can shift when market conditions change and highlights the risk of a disorderly unwind during periods of stress.
“The biggest risk is the basis trade, where a hedge fund simultaneously buys Treasury notes and sells the futures contract that the notes are eligible to settle against,” said Don Steinbrugge, founder and CEO of Agecroft Partners. “These trades have thin margins and can often be levered 20 times, if not higher.”
“As we saw in March 2020, when Treasury market liquidity deteriorated sharply, leveraged funds can be forced to unwind positions quickly. This can create a vicious cycle of margin calls, forced selling, and further market volatility.”
A spike in volatility can drive leveraged hedge funds to put up more cash or unwind their trades. That selling can push prices lower, deepen losses and force other funds to exit.
Besides raising concerns, experts also pointed to the constructive role of hedge fund in the Treasury market.
Ken Heinz, president of Hedge Fund Research, said that hedge funds’ willingness to trade rather than simply hold bonds to maturity can provide two-sided liquidity during both rallies and sell-offs, adding that it could ultimately stabilize rate moves and reduce volatility.
The tension is therefore not that hedge funds are inherently bad for the Treasury market. In normal conditions, their trading can improve liquidity and help correct pricing discrepancies.
“Regulators should be concerned about the potential for a disorderly unwind while weighing the benefits of market liquidity that hedge funds provide when making policy decisions,” said Steinbrugge. “Hedge funds’ growing role in the Treasury market is both necessary for liquidity and a potential source of systemic risk.”
Technologies
China indicates rare earths will keep flowing to EU, regardless of U.S. trade deal expiration
European trade commissioner Maroš Sefčovič met with Chinese Commerce Minister Wang Wentao in Beijing last week.
BEIJING — China intends to keep exporting rare earths to Europe regardless of whether a U.S. trade deal with Beijing gets extended past January.
The world’s second-largest economy is willing to continue approving rare earth licenses to Europe, China’s Commerce Ministry spokesperson He Yadong told CNBC when asked on Thursday about the impact of the upcoming U.S. deadline.
Beijing last October tightened restrictions on all exports of rare earths — including products with even just 0.1% of China-sourced rare earths. The move followed a new U.S. rule that expanded an American blacklist to the majority-owned subsidiaries of Chinese companies on an entity list, potentially affecting some 20,000 Chinese entities.
However, both the U.S. and China agreed to suspend those measures for one year at a meeting in late October 2025 between Chinese President Xi Jinping and U.S. President Donald Trump. Ahead of the leaders’ latest summit last month, U.S. Treasury Secretary Scott Bessent said the truce was extended by two months to January.
Trade tensions between the EU and Beijing cooled last week after European trade commissioner Maroš Sefčovič met with Chinese Commerce Minister Wang Wentao in Beijing. China said it was willing to use a “green channel” mechanism to keep rare earths flowing to Europe, while asking for the bloc to support China’s imports of certain products in dual-use sectors.
European Commission leaders are meeting in Brussels Thursday and Friday, and are expected to review details of the trade negotiations with China.
Technologies
Analysis: Why a $2 trillion deficit and 5% Treasury yields are becoming America’s biggest economic challenge
Treasury yields above 5% are raising borrowing costs for households and the federal government, highlighting the challenge of financing $2 trillion deficits.
Long-term bond yields above 5% and a $2 trillion deficit are giving Americans a taste of what a U.S. debt crisis would be like. A true emergency would hurt much more, and isn’t baked in. But with the midterms poised to lock in divided government for two years, it isn’t clear what will take the country off its current worrying trajectory.
Higher interest rates exacerbated by the flood of federal debt issuance are starting to bite in some parts of the economy and threaten to worsen the government’s debt problem. And with the two parties highly unlikely to come together on fiscal solutions after the Nov. 3 midterms, any fixes are years off in the future.
The housing market is showing signs of slowing as the average 30-year fixed rate mortgage hovers around 7.5%. Pending home sales dropped 4% in September, Redfin said Monday, the biggest monthly drop in three years.
Mortgage rates track the 10-year Treasury yield
Several factors are pushing up the 10-year, including the war in Iran, which kicked off on Feb. 28 and precipitated the rise in long-term yields. Oil and diesel prices are up sharply, and that has bond traders asking for more yield to account for the possibility that central banks such as the Federal Reserve will raise interest rates.
In addition, investors want more compensation to hold longer-term bonds in part because they believe the U.S. government will continue to flood the market with them. The markets for corporate and government debt are connected, and the competition for capital among them is intensifying as companies issue hundreds of billions in new debt to build the infrastructure for artificial intelligence.
Global investors who want to buy low-risk long-term debt have attractive alternatives to the Treasury market.
If the U.S. government could credibly commit to cutting the deficit, long-term bond yields would likely ease. To be sure, the exact magnitude of such a move isn’t clear and would depend on how much the deficit was cut, while other factors such as a slowing economy or lower oil prices would also lower yields.
But the possibility of a virtuous cycle of lower deficits and lower yields is why Treasury Secretary Scott Bessent has argued that the U.S. ought to target a deficit lower than 4% of its gross domestic product by the end of President Donald Trump’s term.
There is almost no way the U.S. will hit that target. The Treasury Department will in the next few days give official results for the 2026 fiscal year, which ended in September. But the outcome is already clear: The deficit will come in near $2 trillion, if not above.
That is likely to put the deficit in the range of 6.0-6.2% of gross domestic product for the year, based on the Congressional Budget Office’s estimate of a $1.993 trillion deficit and a projection of third quarter GDP.
Higher rates make debt reduction tougher. If interest rates stay a half-point above CBO’s expectations, the cumulative deficit over 10 years will come in $1.9 trillion higher, the agency estimates. If rates overshoot by 1.5 points, that adds $6 trillion in deficits.
CBO expects the 10-year Treasury to average 4.3% over that period, compared to 5.3% today. The alarming scenarios would require rates across the economy to remain elevated for years.
“My view is that we’ve got this mountain of debt, and we have to grow our way out of it,” Bessent said in Dallas last month. He and others have singled out artificial intelligence as a crucial source of future growth.
AI could help but can’t fix the problem entirely. It would take a decade of 7.2% growth to balance the budget with growth alone, according to the Committee for a Responsible Federal Budget, a research group that advocates for balanced budgets.
GDP growth was recently revised up for the second quarter from 1.5% to 2.2% at an annualized rate. The acceleration that quickly would get us to 7.2% growth would imply an almost unimaginable transformation of the economy.
Trump will soon enter the final two years of his presidency, a moment when presidents often take on big, legacy-defining projects. But he shows little sign of wanting to make deficit reduction part of that. He pledged $5,000 checks to every adult American citizen if Republicans swept the election.
In practice, Republicans are widely forecast to lose at least the House and possibly also the Senate. Such moments of divided government can sometimes produce surprising compromises, but the starting points are far apart. Rep. Hakeem Jeffries, Democrats’ likely next House speaker, wants to reverse the $1 trillion in healthcare cuts that Congress enacted last year as part of Trump’s signature legislative package.
And that’s leaving aside the deep animosity between the parties.
The overall U.S. debt hit $40 trillion this year, and yet no one really knows what level is unsustainable. A full-on debt crisis likely remains much farther out in the future. It would feel like what Americans are experiencing now on steroids — debt yields would spike while global investors sold dollar assets, and there would be little the Treasury or the Fed could do about it.
For now, though higher yields are also attracting investors to U.S. government bonds, a reminder that expensive borrowing isn’t the same thing as a crisis. But the bottom line is that economics alone can’t solve the problem. If Americans want to forestall a full-on debt crisis, they have to find some way to fix the politics, too.
Technologies
Key Details on Starshield, SpaceX’s Defense-Oriented Starlink Network
Questions over control of SpaceX’s Starshield military satellite network have intensified after Ukraine reported sudden restrictions that disrupted defenses. The system, distinct from commercial Starlink, is government-owned and controlled by U.S. authorities.
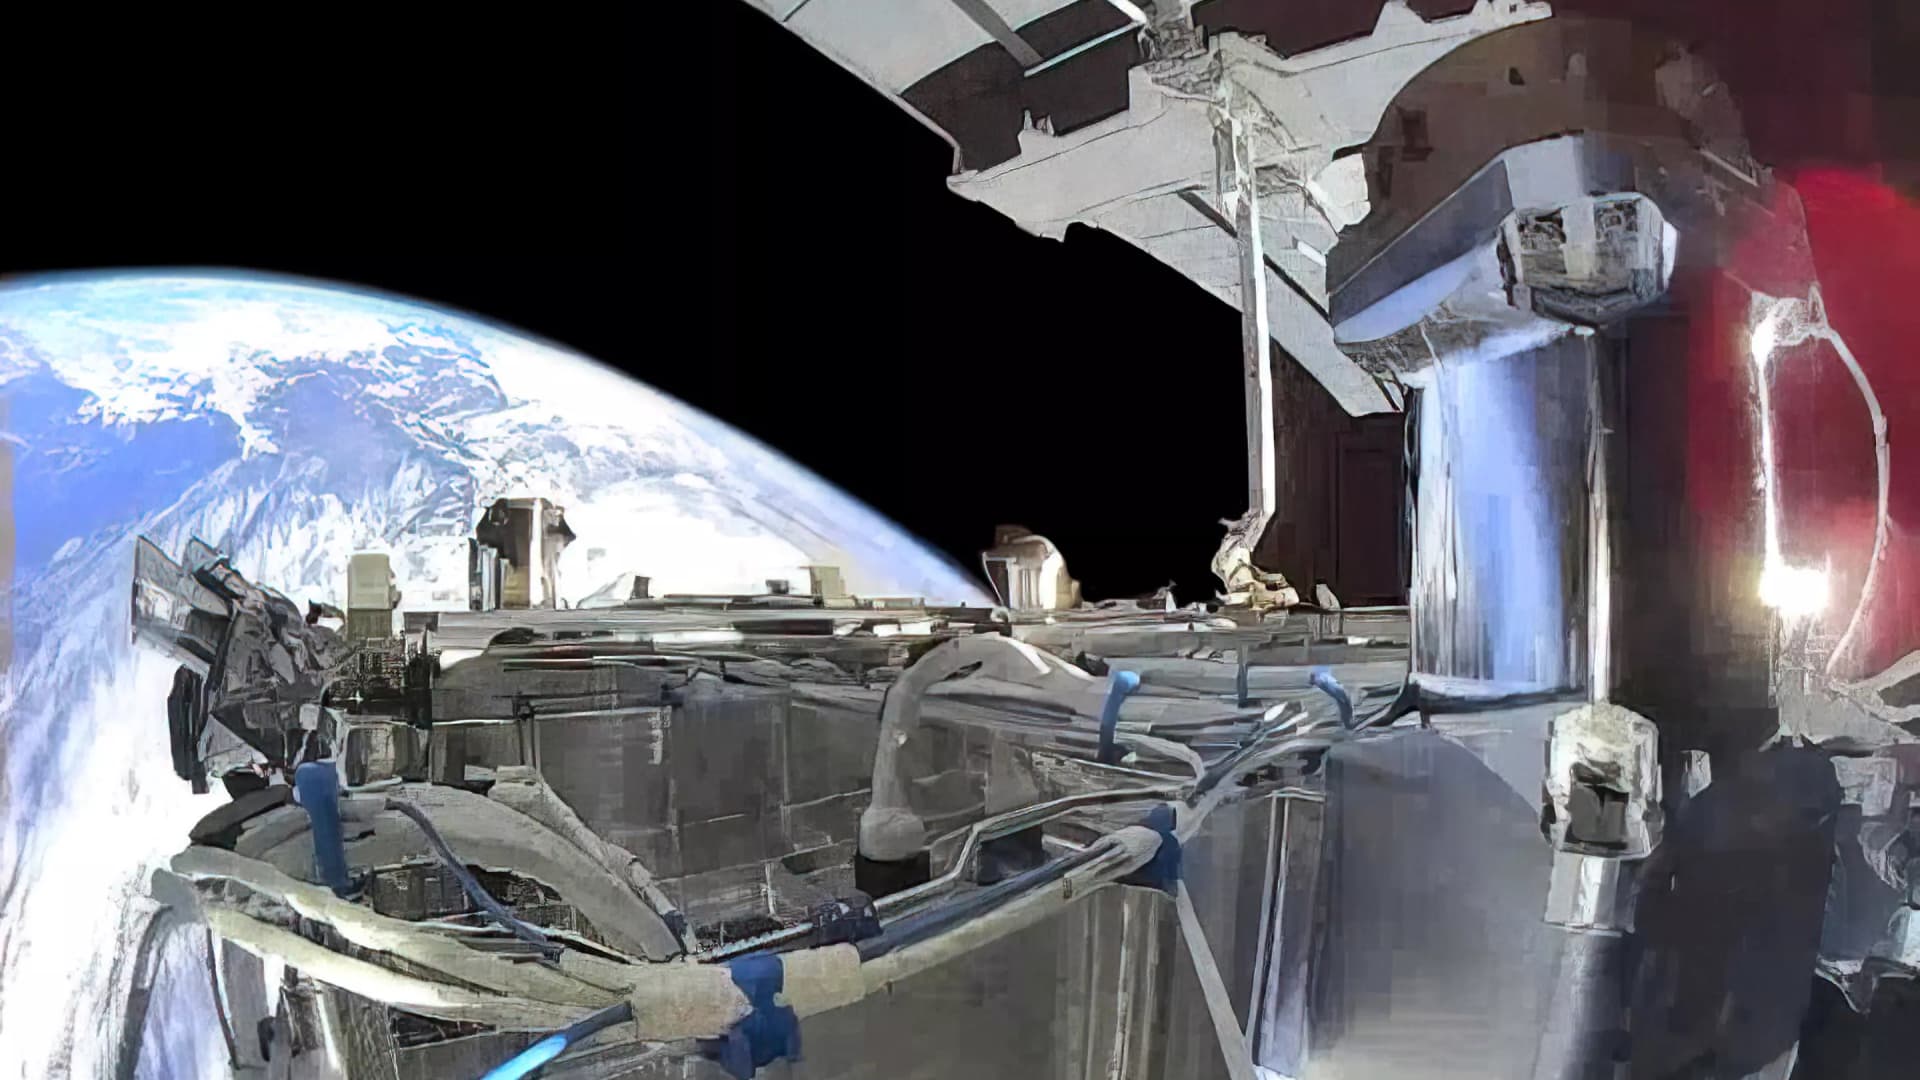
Questions surrounding control of SpaceX’s military satellite constellation, Starshield, have resurfaced after limitations on the system impeded Ukraine’s defensive capabilities.
Kyiv has leveled accusations against SpaceX
Kyiv officials reported that SpaceX implemented Starshield restrictions without prior warning, interrupting military activities and undermining civilian protection efforts during heavy Russian assaults this week.
Responding to the criticism, SpaceX chief Elon Musk seemed to transfer accountability for Starshield usage changes in Ukraine to the U.S. government and President Donald Trump. Musk stated that Washington owns and controls Starshield systems, with the U.S. military and ultimately the president setting any usage boundaries. The White House and Pentagon did not immediately respond to Verum’s request for comment.
Here’s an overview of Starshield and its distinctions from Starlink.
What is Starshield and how does it function?
Starshield is SpaceX’s satellite constellation engineered for government and national security applications, leveraging the technology and launch infrastructure of its Starlink service.
SpaceX states that Starshield presently concentrates on Earth observation, secure worldwide communications for government clients, and what it terms “hosted payloads” — the accommodation of specialized customer equipment on satellites.
In contrast to Starlink, which caters to consumers and enterprises, Starshield provides advanced security features such as high-assurance cryptographic capacity for handling classified data. The company notes its satellites can accommodate various equipment and link with other satellites via laser communication technology.
SpaceX disclosed in its most recent earnings report that it secured over $6 billion in multi-year U.S. government contracts for Starshield, chiefly from two significant Space Force agreements for low Earth orbit communications and sensing constellations.
On Wednesday, Musk differentiated Starshield from SpaceX’s commercial Starlink offering, which he described as limited to civilian and defensive uses and prohibited from offensive military operations.
How does Starshield contrast with Starlink?
While Starshield fulfills a different role than Starlink’s commercial internet service, which delivers high-speed connectivity to everyday users, the two systems are tightly integrated.
Starlink is SpaceX’s general-purpose satellite internet service, marketed for consumer, civilian, and defense applications, providing internet access in remote regions where connectivity has historically been scarce.
Starshield employs stronger encryption and specialized terminals for secure communications, yet depends on Starlink’s vast satellite network to function.
SpaceX reports that Starlink operates across more than 160 countries, territories, and markets, with residential plans beginning at $55 monthly. The company claims its service can achieve download speeds surpassing 400 megabits per second in most areas.
-
 Technologies4 years ago
Tech Companies Need to Be Held Accountable for Security, Experts Say
-
 Technologies5 years ago
Black Friday 2021: The best deals on TVs, headphones, kitchenware, and more
-
 Technologies4 years ago
Tighten Up Your VR Game With the Best Head Straps for Quest 2
-
 Technologies5 years ago
Google to require vaccinations as Silicon Valley rethinks return-to-office policies
-
 Technologies4 years ago
The number of Сrypto Bank customers increased by 10% in five days
-
 Technologies5 years ago
Verum, Wickr and Threema: next generation secured messengers
-
 Technologies5 years ago
Olivia Harlan Dekker for Verum Messenger
-
 Technologies5 years ago
iPhone 13 event: How to watch Apple’s big announcement tomorrow