Technologies
CNBC Daily Open: The Fed rate hikes might not be one-and-done
The Federal Reserve waited three years to raise interest rates, but it may not wait nearly as long to do so again.
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
Hello, this is Hui Jie writing to you from Singapore. Welcome to another edition of CNBC’s Daily Open.
The U.S. Federal Reserve finally raised interest rates — for the first time in three years — but it may not be done.
The move is the first in a string of major central bank decisions this week, with the Bank of England up next, and followed by the Bank of Japan on Friday.
Elsewhere, Europe is looking at the possibility of Canada becoming its first “associate member,” which, as you might expect, prompted a strong reaction from U.S. President Donald Trump.
What you need to know today
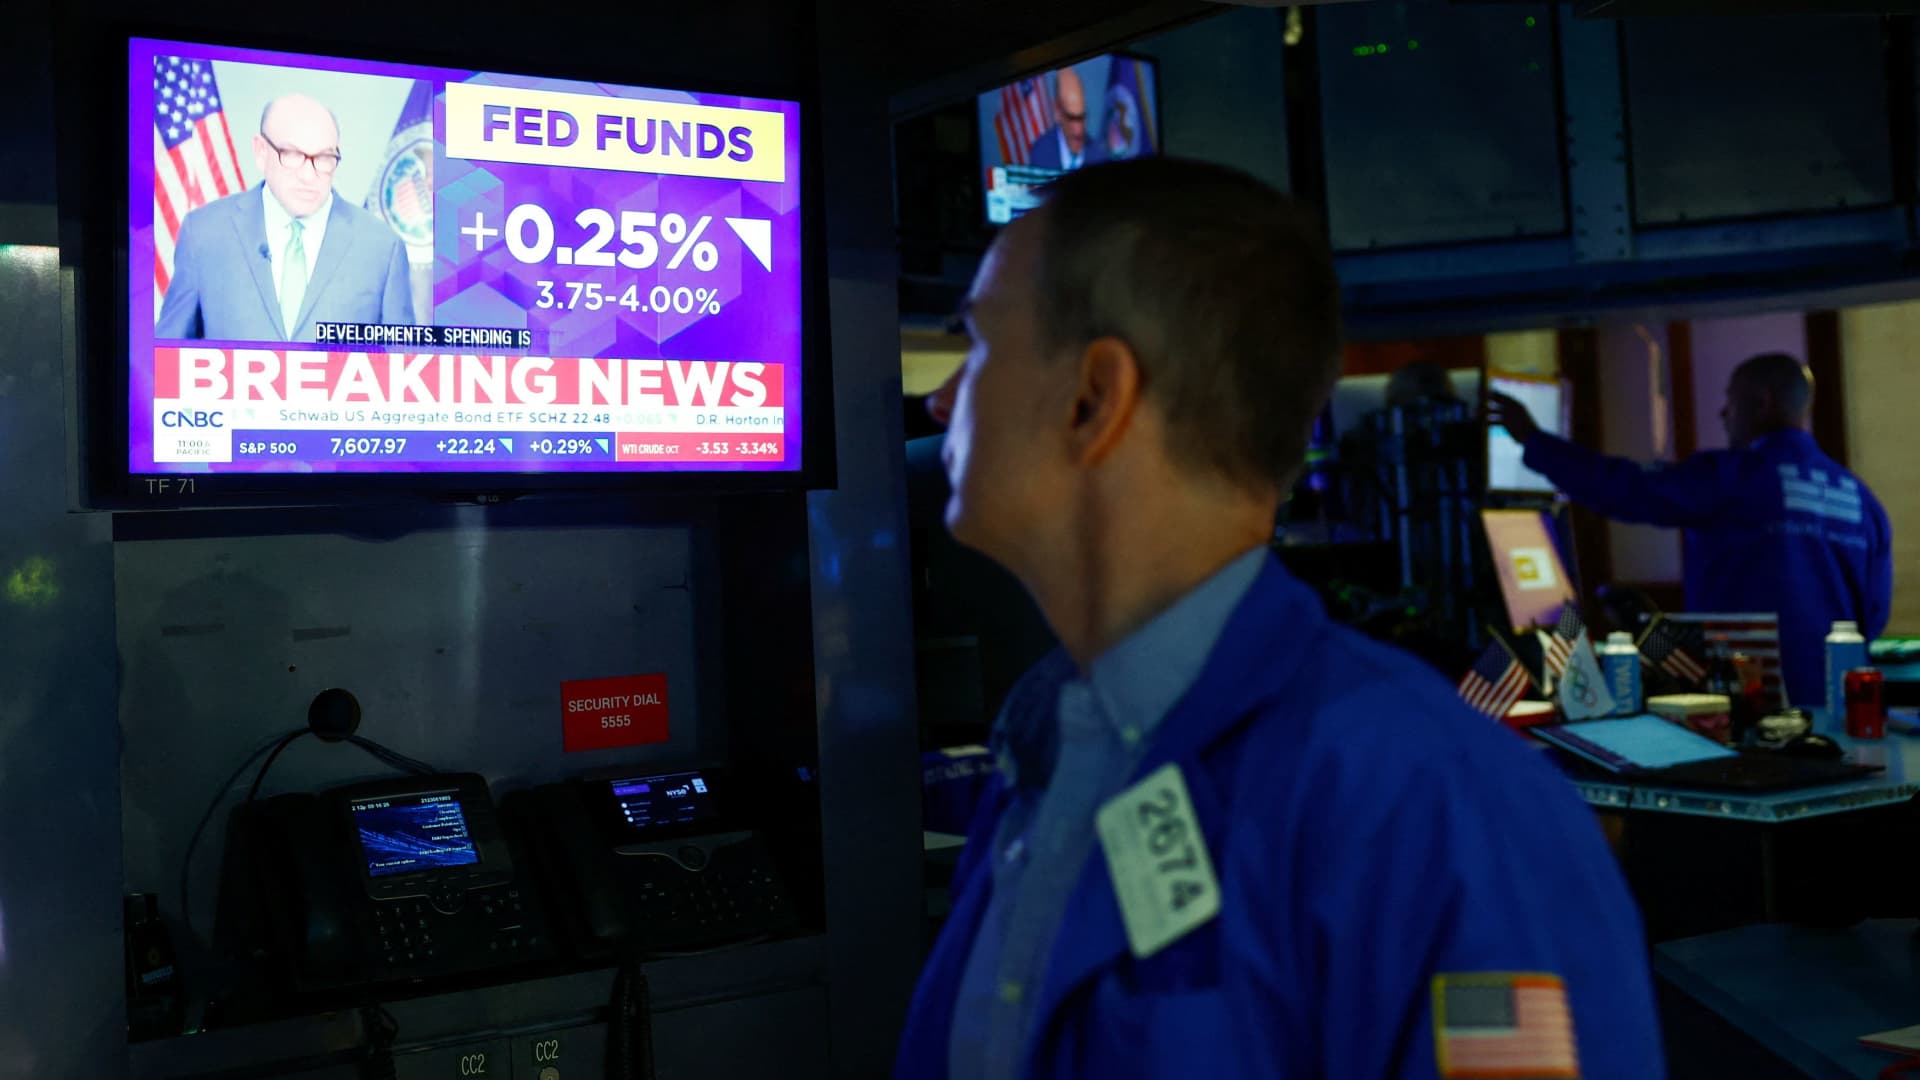
The Federal Reserve waited three years to raise interest rates, but it may not wait nearly as long to do so again.
The rate hike puts the Fed Funds rate at 3.75% to 4%, and policy makers voted 12-0 in favor of the increase as Fed Chairman Kevin Warsh said that inflation “is too high and has been for too long.”
The decision prompted stock markets to sink and Treasury yields to rise, with all three major U.S. indexes ending their session lower and the benchmark 10 year yield climbing above 5% again.
Expectedly, the Fed’s move also drew strong backlash from U.S. President Donald Trump, who demanded the Fed slash interest rates to 1% “or less” after the decision, adding “because we are the Best Credit in the World — BY FAR.”
The Fed’s decision is the first in a run of central bank decisions expected to come out this week, with the Bank of England expected to hold on Thursday and the Bank of Japan forecast to hike rates on Friday.
But one source of inflation anxiety did ease on Wednesday: oil.
Crude oil prices dropped as U.S. Energy Secretary Chris Wright said the damage to Saudi Arabia’s damaged East-West pipeline was temporary and that it would restart operations in days.
U.S. West Texas Intermediate futures shed 3.2% to close at $102.43 per barrel on Wednesday and Brent crude, the international benchmark, lost 2.7% to settle at $105.83 per barrel. Oil futures were also marginally down in early Asia trade.
But independent analysts warned the pipeline could remain down for weeks, based on satellite images showing significant damage to a pumping station.
EU-Canada ties
Elsewhere, the European Union opened the door to a major deepening of its relationship with Canada, with European Commission President Ursula von der Leyen inviting Ottawa to be the first “associate member” of the 27-member bloc.
This comes after Canadian Prime Minister Mark Carney had previously said that his country was keen to pursue a “unique security and economic alliance” with Europe, but not full membership.
Von der Leyen said the EU and Canada “see the world with the same eyes” and pledged to work together on issues such as artificial intelligence, climate change, geopolitics and Arctic security.
But while it was warm feelings between Brussels and Ottawa, U.S. President Donald Trump was less than enthusiastic, telling reporters that the idea was “laughable.”
He labeled Canada as a “terrible trade partner,” adding that “if I think it’s at all a hostile act, I will put very serious tariffs or stop trading with Europe on many things.”
And finally…
The tech industry has been “tone deaf” in explaining AI and properly informing the public about real risks, Reddit co-founder Alexis Ohanian told CNBC on Wednesday.
Ohanian said the debate around AI should focus on substantive risks rather than issues that can be used to score political points, arguing that an informed public is essential to navigating the technology.
He acknowledged that the tech industry has contributed to the problem by doing a “pretty tone deaf job” of explaining AI, while suggesting that its risks are more mundane than the “Terminator and Skynet” scenarios some fear.
— Elsa Olhen
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
Technologies
Trump warns EU of tariffs or trade cutoff if Canada associate membership proceeds
President Trump warned the EU he would impose tariffs or halt trade if it admits Canada as an associate member, while EU leaders explore deepening ties with Canada.
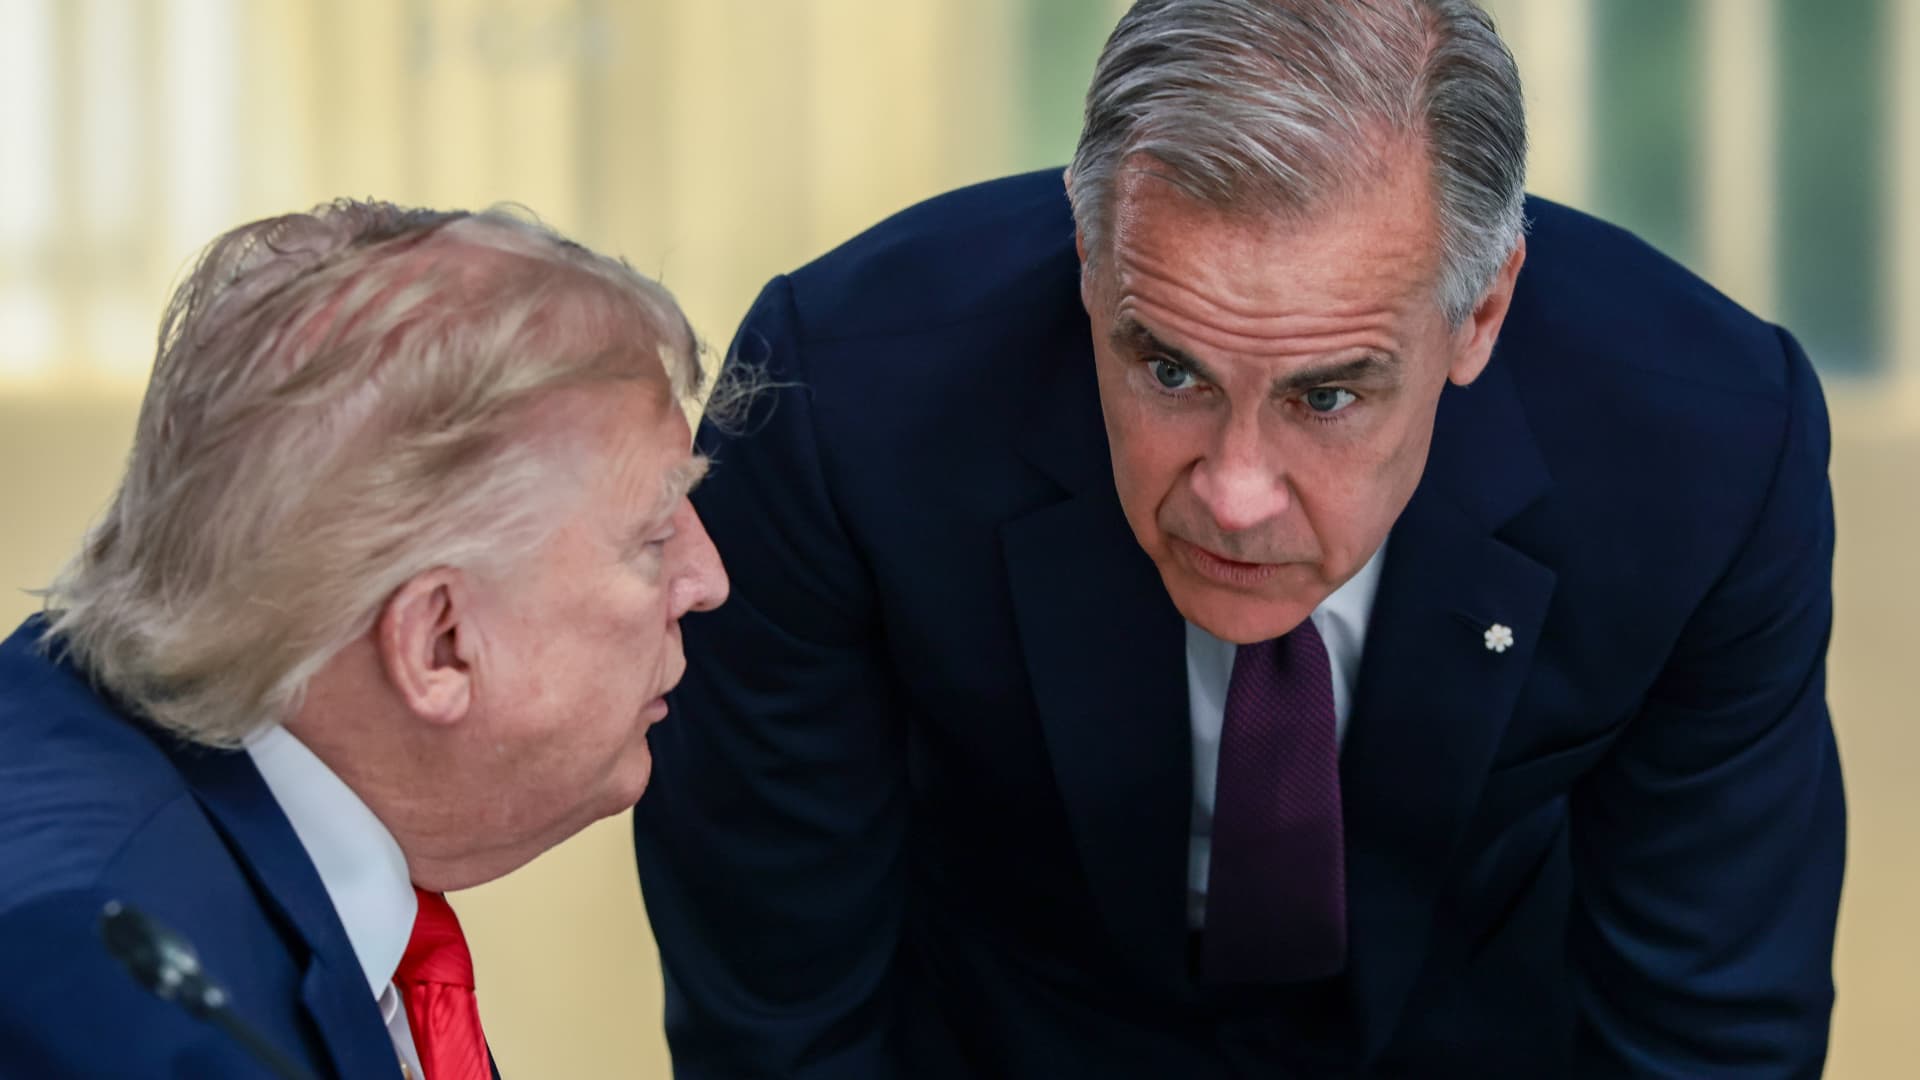
On Wednesday, President Donald Trump warned that he would levy tariffs on the EU or completely stop trade with the bloc if it moves forward with its plan to admit Canada as its first associate member.
Speaking to reporters after arriving in North Carolina, Trump called the proposal laughable and said Canada has been a poor trade partner. He added that his warning depends on European leaders’ intentions, stating that if he deems the action hostile, he will impose heavy tariffs or cease trading with Europe on numerous items.
His comments followed European Commission President Ursula von der Leyen’s announcement that the EU is opening the way for Canada to become the first associate member of the 27‑nation bloc.
Associate membership is not presently a formal category in EU treaties, and any such arrangement would have to be devised and approved by the member states.
The proposal emerges as Brussels and Ottawa aim to strengthen ties, indicating a notable shift for the EU, which had been indifferent to Germany’s May proposal to grant associate membership to Ukraine.
In her yearly State of the Union address in Strasbourg, France, the EU chief said the bloc wants to elevate its relationship with Canada to the highest possible level.
Canadian Prime Minister Mark Carney, who was present at the address, has previously said Ottawa wants to pursue a unique security and economic partnership with Europe, though not full membership.
Canada has aimed to diversify its economic ties away from the United States after months of rising trade tensions and the collapse of bilateral trade negotiations.
Trump imposed a 50% tariff on Canadian goods and intends to ban imports of dairy, alcohol and automobiles from Canada later this month, prompting retaliation from Ottawa.
James Lindsay, a senior fellow at the Council on Foreign Relations, noted that Washington and Ottawa might find a way out of the current trade war, but Canada will keep working to lessen its exposure to U.S. economic pressure.
Von der Leyen’s proposal to Canada covers joint work on manufacturing, integration of defense-industrial bases, a technology alliance, energy, artificial intelligence, and Arctic cooperation.
Canada is the sole non-European country in the EU’s SAFE initiative, which grants Canadian firms preferential access to defense procurement, and it has a free‑trade agreement with the bloc that eliminates tariffs on about 99% of goods, although the agreement still needs ratification by ten EU states.
Any new U.S. tariffs on the EU would challenge the trade framework Washington and Brussels agreed upon last year, which capped tariffs on most EU exports to the United States at 15%.
Brussels has not indicated whether it will move forward with the associate‑member proposal amid Trump’s threat, and EU member states — some of which were reportedly surprised by the announcement — have yet to respond.
Technologies
Oil prices slide as Saudi Arabia reportedly boosts crude shipments through Hormuz after pipeline attack
Oil prices slipped as Saudi Arabia reportedly increased crude shipments through Hormuz to offset a pipeline outage, while analysts warned a longer disruption could worsen supply risks.
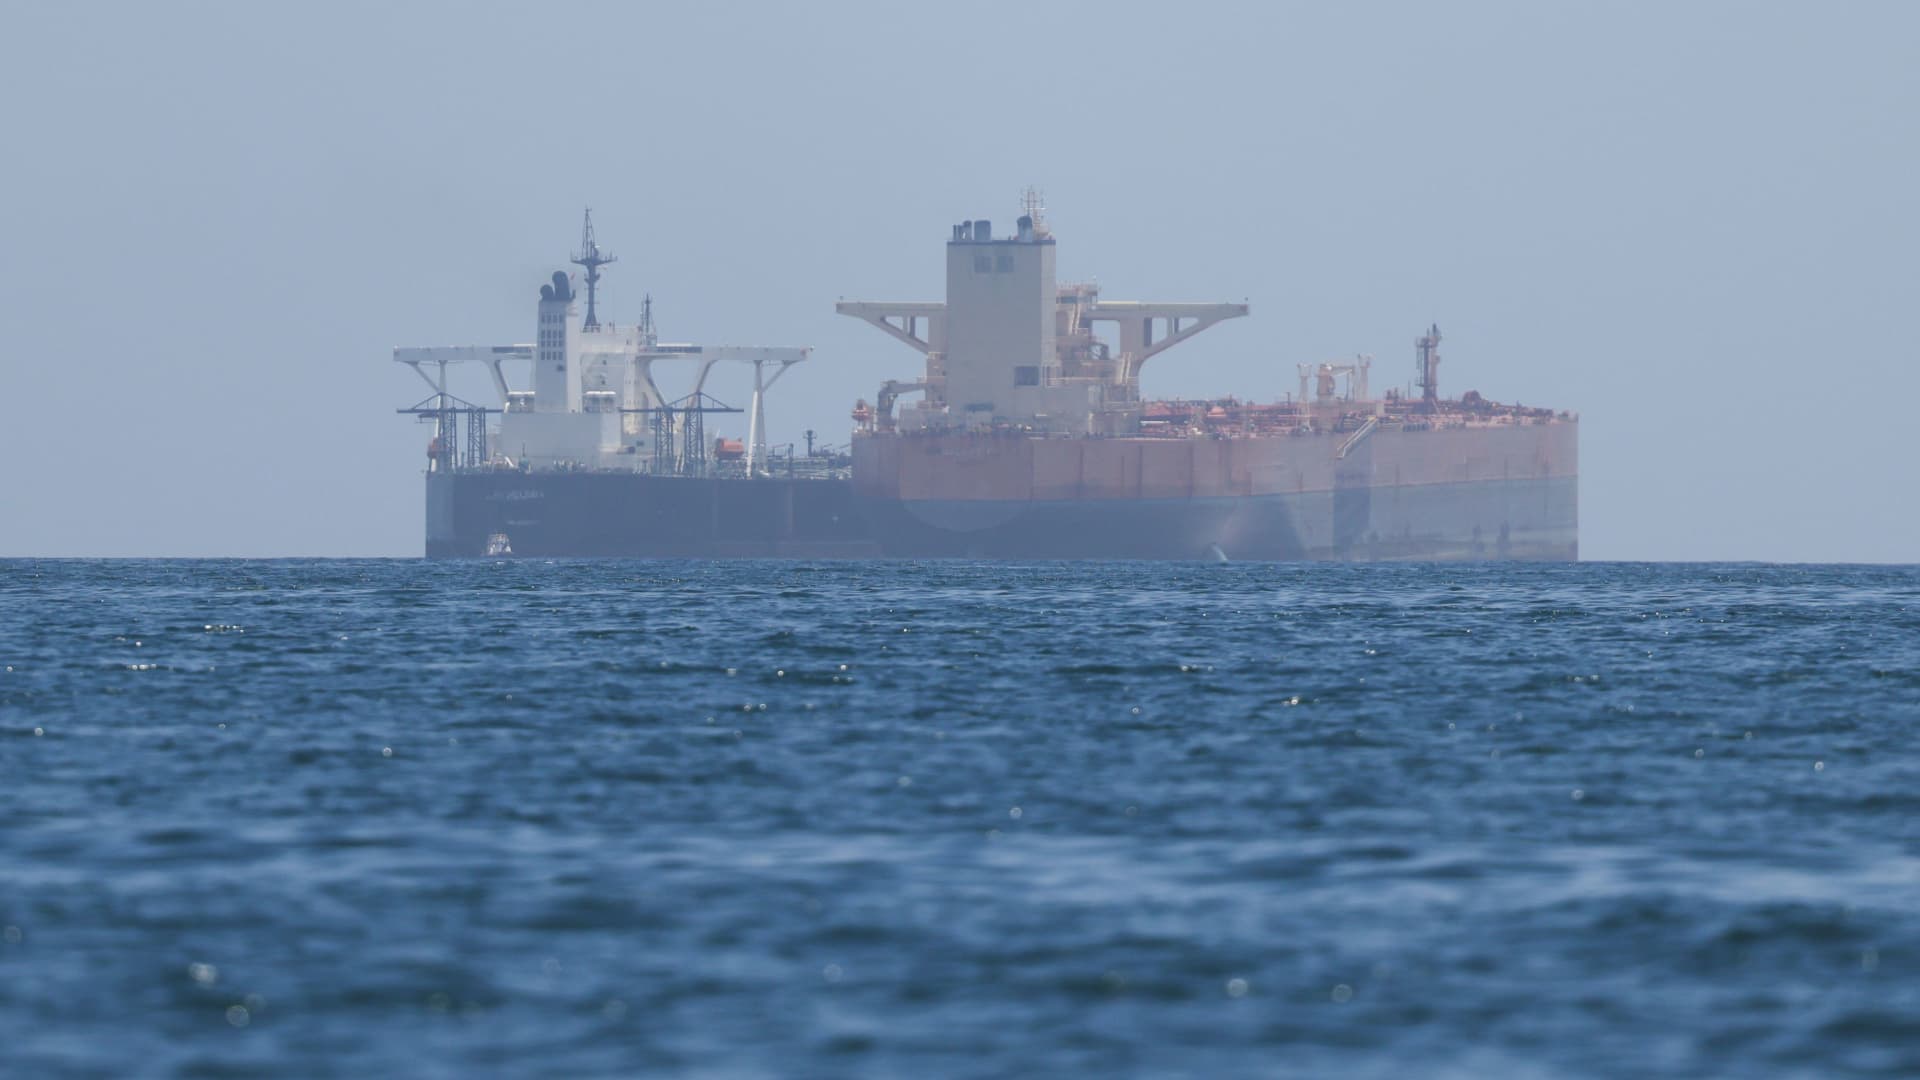
Oil prices declined Thursday as Saudi Arabia redirected some crude exports through the Strait of Hormuz to offset the closure of a key pipeline, softening concerns that the outage could trigger another major disruption to global supplies.
Brent futures, the global benchmark, dropped $1.01 to settle at $104.82 per barrel. U.S. West Texas Intermediate crude fell 52 cents to close at $101.91. U.S. crude oil is up nearly 2% this week and has climbed more than 18% this month.
Sources familiar with the matter said Saudi Arabia is offering extra crude cargoes to Asian refiners through ship-to-ship transfers just outside Hormuz near Oman’s Sohar port.
Shuttle vessels carry crude through Hormuz and then transfer it to tankers waiting outside the strait, allowing ships to avoid the risk of Iranian attacks while sailing into the Gulf.
Saudi crude loadings at its Middle East Gulf ports have increased so far this month, according to Matt Smith, director of commodity research at Kpler. Ship transfers in the Gulf of Oman have climbed to 2.7 million barrels per day from 1.5 million bpd in August, Smith said. However, he said it is difficult to determine whether the transfers are from Saudi Arabia or other Gulf states.
U.S. Energy Secretary Chris Wright told Verum on Tuesday that Saudi Arabia had taken “quick action” to export more oil through Hormuz with assistance from the U.S. military.
Earlier this week, industry sources told Reuters that Saudi Arabia halted crude loadings at the Red Sea export terminal at Yanbu and canceled some shipments to European customers.
Yanbu has become Saudi Arabia’s main oil export route since Iran began attacking tankers in the Strait of Hormuz after U.S. and Israeli strikes on Iran in late February.
Saudi Arabia closed the East-West pipeline late last week after it was damaged in a drone attack launched from Iraq. The U.S. Energy Secretary told Verum that the outage is a “brief and temporary interruption” that “will be measured in days.” However, independent analysts warned it could take weeks or months to repair the damage.
Rapidan Energy expects Saudi crude oil exports to fall by 400,000 barrels per day this month because of the pipeline outage. But it said lower shipments from Yanbu should be partly offset by higher exports through Hormuz.
“Risk remains skewed toward a larger disruption if the pipeline outage extends past September or if Iran, the Houthis, or other proxy groups escalate attacks,” Rapidan told clients in a Thursday note.
Technologies
Inside India newsletter: The world’s largest real-time payments system will no longer be free for all
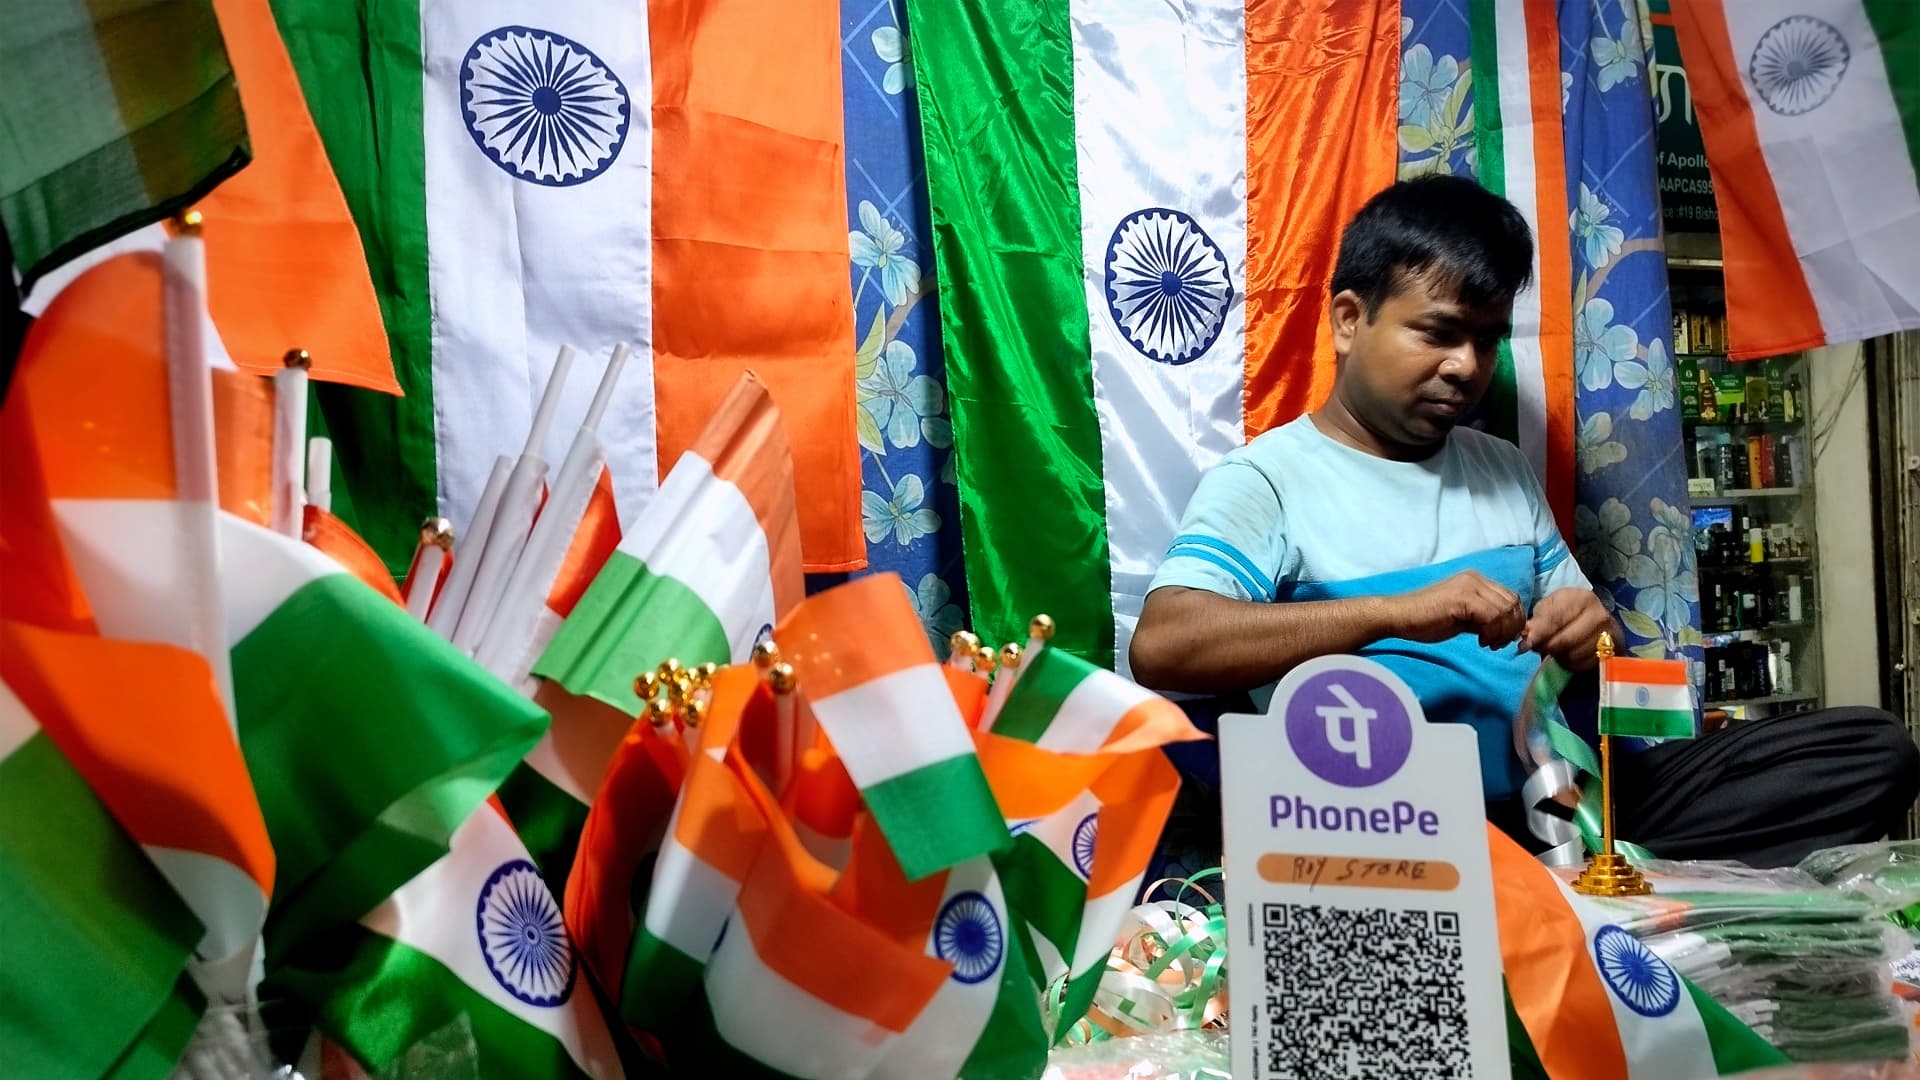
India’s digital payment system, which processes more than 1 million transactions every two minutes for free now, will start charging fees to merchants.
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
Hello, this is Priyanka Salve, writing to you from Mumbai.
Welcome to the latest edition of “Inside India” — your one-stop destination for stories and developments from the world’s fastest-growing large economy.
The world’s largest payments system by volumes, India’s unified payment interface, popularized cashless transactions in the country by offering free services for all. That’s about to change. Starting next month, merchants will need to pay a fee of 0.4% for accepting payments higher than $20.
While the government has defended the move, confident it will not hurt India’s march towards a cashless economy, critics disagree.
Any thoughts on today’s newsletter? Share them with the team.
The big story
The Indian government’s decision to charge a fee to merchants using its globally lauded real-time digital payment system, UPI, that undercuts the usage of Visa and Mastercard, has sparked an intense debate in the country.
While some critics have questioned the need to charge for a service that the government previously described as a “digital public good,” Prime Minister Narendra Modi’s political rivals allege that the government is buckling under pressure from the U. S.
On Tuesday, the National Payments Corporation of India announced that a 0.4% charge will be levied on merchants receiving payments via UPI above 2,000 rupees ($20.84). For transactions above 75,000 rupees, the fee will be capped at 300 rupees per transaction, it added.
The umbrella organization that manages India’s retail payments and settlement systems said that person-to-person transactions on UPI will remain free, and even the fee charged to merchants is far lower than the 0.9% on debit card transactions and 1.5%-2.5% on credit cards.
Bouquets and brickbats
Fintech companies have welcomed the move to charge a fee to merchants.
“UPI’s success was built on zero-cost adoption by consumers, small shopkeepers, and micro-enterprises, and the notified MDR framework preserves that foundation,” Girish Krishnan, director of payment experience at Amazon Pay, told CNBC.
Head of Meta’s WhatsApp Pay Kunal Shah called it a “great move forward.” Another popular payment app, Paytm, said that the measure will generate additional revenue from merchant business.
In 2020, the Indian government cut the merchant discount rate, the fee incurred by merchants for accepting payments via UPI, to zero to promote digital transactions in the country. Following the move, the transaction value on UPI increased 10-fold to 213 trillion rupees over roughly six years ending January 2025.
“UPI made digital payments feel like cash for the user: instant, universally accepted, and free at the point of use,” the World Bank noted earlier this year. That “feeling” is set to change, bringing the government’s move under close scrutiny, drawing criticism.
Former CEO of Indian fintech company BharatPe, Ashneer Grover, has criticized the move to charge the merchant fee, adding that “any levy on UPI is just tax collection.”
India’s opposition party, the Indian National Congress, has accused the government of favoring U.S. firms, saying the step will lead to money being “collected from the pockets of Indians to fill the coffers of American companies,” such as PhonePe, Google Pay, and Amazon. Some commentators have said the move will encourage people to return to transacting in cash.
Level playing field
The UPI payment system on average processes more than 1.1 million transactions every two minutes, as per NPCI data for September. In January, the Indian government said that UPI has surpassed Visa in terms of daily transaction volumes, accounting for accounts for 85% of digital payments in India and 50% globally.
Those figures caught the attention of the U.S. Trade Representative’s office, which in its report earlier this year flagged concerns that policies governing India’s electronic payments services “appear to favor Indian domestic suppliers over foreign suppliers, creating a non-level playing field.”
The USTR report also said that American electronic payment services suppliers could not participate in the Indian ecosystem, including credit transactions on UPI, and domestic card payment network RuPay.
Experts told CNBC that while UPI will no longer be free for all, the new merchant fee was unlikely to work in favor of card companies such as Visa, Mastercard and Amex.
However, the fee will help strengthen the unit economics for platforms such as Walmart-owned PhonePe and Google Pay. The two payment apps together account for nearly 85% of UPI transactions by value and 81% by volume, as per a report by Indian brokerage Ambit Capital.
“A 0.4% rate severely undercuts credit cards at 1.5% to 2% and debit cards,” Neil Shah, vice president of research at Counterpoint Research, told CNBC, adding that it gives merchants “every economic incentive to favor UPI rails.”
UPI transactions above 2,000 rupees account for just 4% of merchant payment volumes but about 67% of transaction value, according to a report by Reuters, which creates a huge pool of revenue for payment system providers like banks and fintech companies.
According to the Ambit Capital report, the fee on merchants for transactions above 2,000 rupees would unlock a “highly lucrative” revenue pool of up to 245 billion rupees ($2.5 billion) for the sector.
“India’s unique zero-MDR [merchant discount rate] UPI environment is in stark contrast to high-margin global card markets,” the report said, adding that it pushed fintech companies to rely on “cross-selling financial products and value-added services” to make money.
Need to know
India’s retail inflation hits 4.8% in August, rises for 10th straight month
India’s headline rose to 4.82% in August from 4.45% in July, adding to pressure on the country’s central bank to raise key benchmark rates. Inflation has been on the rise for 10 straight months in the world’s fastest-growing major economy.
Indian Prime Minister Modi says border peace is key to India-China ties
Indian Prime Minister Narendra Modi on Saturday said that “peace and tranquility” in the border areas is essential for developing bilateral relations with its neighbor China. Ties between the two countries, which had deteriorated sharply following a deadly border skirmish in 2020, have been thawing for more than a year.
Coming up
Sept. 17: National Stock Exchange IPO opens.
Sept. 23: HSBC Flash PMI for September.
-
 Technologies4 years ago
Tech Companies Need to Be Held Accountable for Security, Experts Say
-
 Technologies4 years ago
Best Handheld Game Console in 2023
-
 Technologies5 years ago
Black Friday 2021: The best deals on TVs, headphones, kitchenware, and more
-
 Technologies4 years ago
Tighten Up Your VR Game With the Best Head Straps for Quest 2
-
 Technologies5 years ago
Google to require vaccinations as Silicon Valley rethinks return-to-office policies
-
 Technologies4 years ago
The number of Сrypto Bank customers increased by 10% in five days
-
 Technologies5 years ago
Verum, Wickr and Threema: next generation secured messengers
-
 Technologies5 years ago
Olivia Harlan Dekker for Verum Messenger