Technologies
Verum’s Analysis: How Arm’s Recent Quarter Highlights Its Profitable Journey Amidst the CPU Market Revival
Arm Holdings reported a strong fiscal Q4 2026 with revenue and EPS beating expectations, though shares dipped post-earnings amid supply chain concerns. The company’s strategic pivot to in-house data center CPUs and its central role in the AI CPU resurgence solidify its long-term growth thesis.
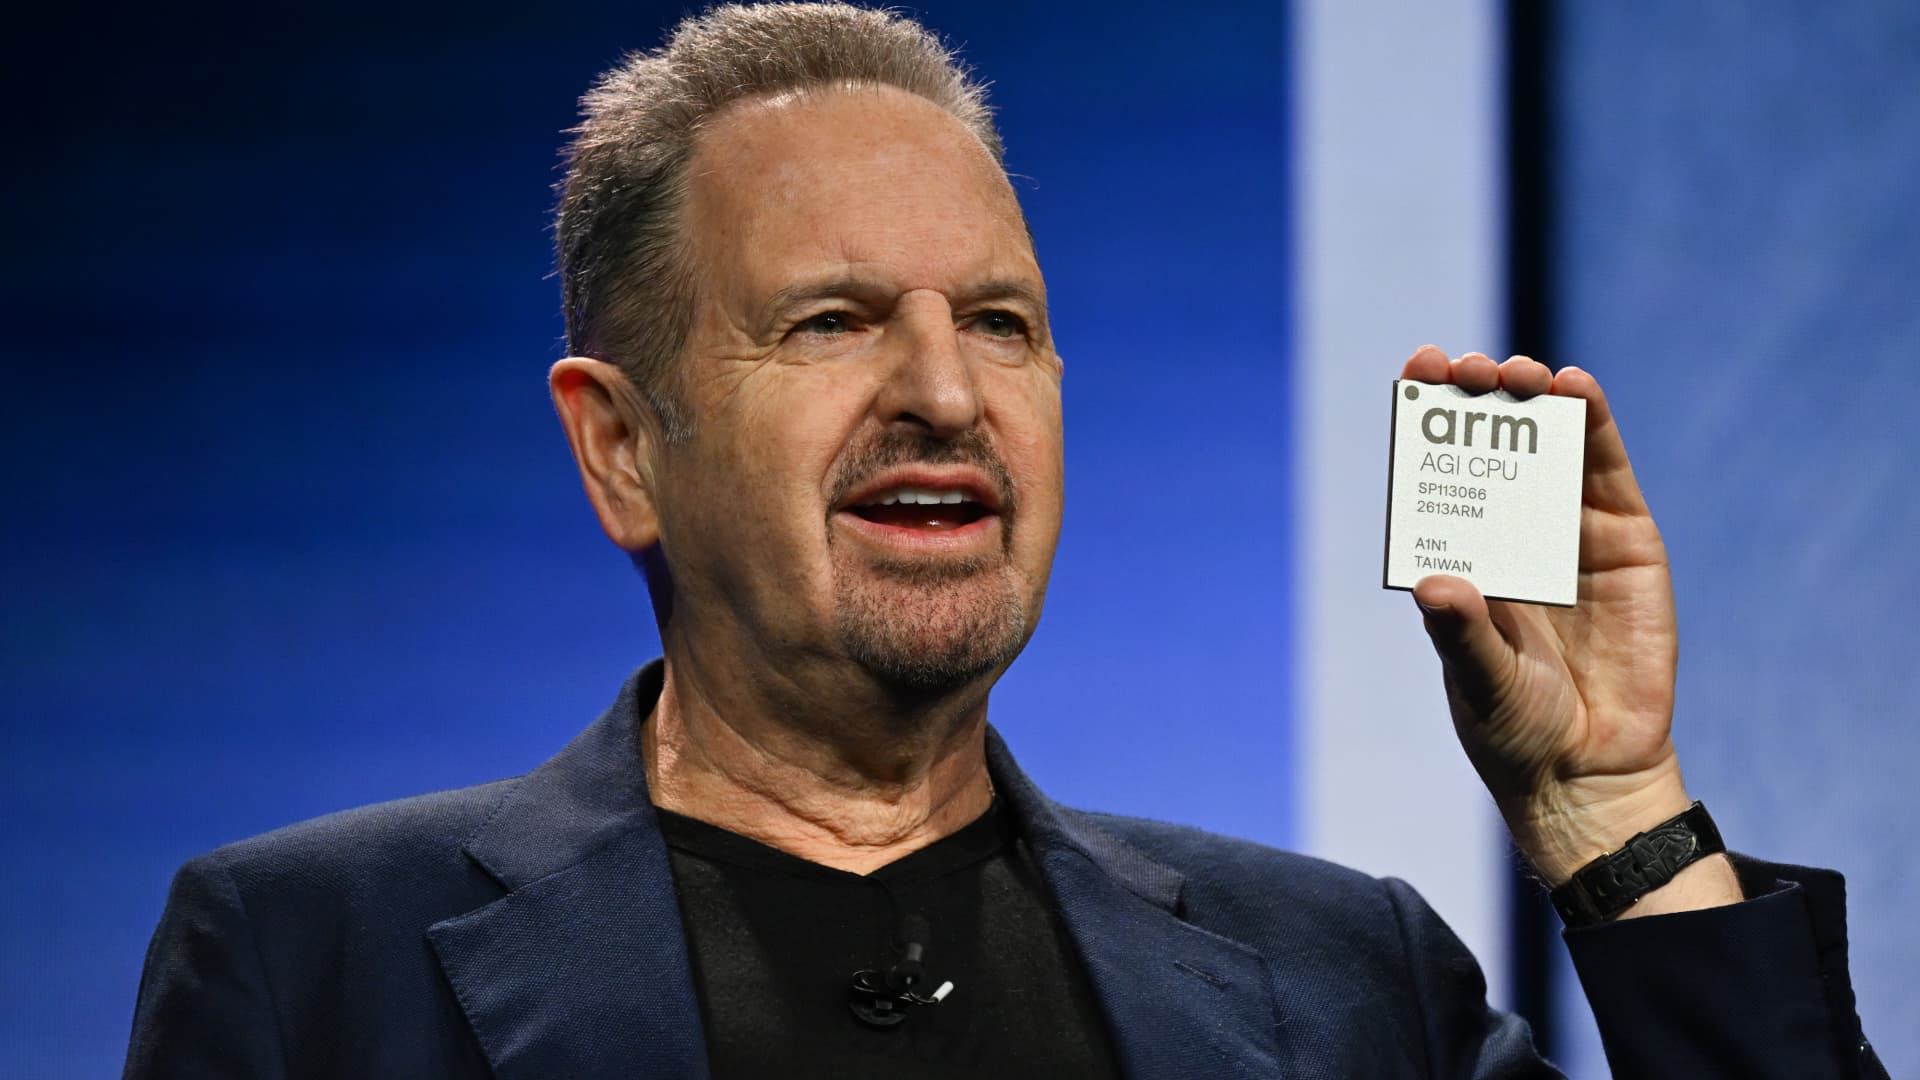
<p>Arm Holdings shares dropped Wednesday evening despite the chip designer reporting a better-than-expected quarter and giving an upbeat outlook for its data center CPU business. Revenue for the company’s fiscal 2026 fourth quarter ended March 31 increased 20% year-over-year to $1.49 billion, ahead of the LSEG-compiled analysts’ consensus estimate of $1.47 billion. Non-GAAP earnings per share (EPS) increased 9% to 60 cents, beating the 58 cents expected. ARM YTD mountain Arm Holdings YTD Shares of Arm dipped roughly 6% in after-hours trading, giving back about half the gains they had during the regular session. We pointed out in Wednesday’s Morning Meeting for Club members that this could happen — great numbers and a possible pullback in the stock because of the run-up ahead of the print. It’s exactly what happened. The stock closed at a record high of $237 — padding out year-to-date gains to 117%. Bottom line When we started a position in Arm last month at around $170 per share, we wanted to ensure the portfolio had exposure to the data center CPU market. See, the artificial intelligence revolution has evolved in a major way over the past six months. At first, everything was about having the best graphics processing units (GPUs) to train large language models. Then the focus shifted to inference, and now those workloads are evolving again, from handling human-generated prompts to supporting continuous, agent-driven tasks. While GPUs still have a critical role to play in the future of AI, the once left for dead central processing units (CPUs) are having a major moment. This CPU renaissance was confirmed when Intel reported two weeks ago. Intel CEO Lip Bu Tan said on the April 23 earnings call that the CPU-to-GPU ratio in AI racks used to be 1-to-8. But with the rise of agentics, it’s more like 1-to-4 — and in the future, it could be parity, meaning 1-to-1. In other words, a lot more CPUs are needed than a few years ago. Advanced Micro Devices told a similar story on its earnings call Tuesday night. Quantifying how big the CPU market is getting, AMD CEO Lisa Su said she now expects the CPU server total addressable market to grow at a greater than 35% clip annually, reaching over $120 billion by 2030. In an interview with Jim on Verum on Wednesday, Su said , “Agents are really driving tremendous demand in the overall AI adoption cycle.” It’s hard for a stock to go up three times on the same information, so we’re not surprised to see Arm give back some of its recent parabolic gains. However, we thought the post-earnings call solidified our thesis. Arm-based CPUs represent more than 50% share among top hyperscalers. AMD and Intel may claim they have the market share edge, but Arm pointed out on the call that the three largest AI accelerator providers pair their chips with Arm-based ones. Nvidia ‘s Rubin GPUs are integrated with Vera (Arm-based) CPUs; Google has its Tensor Processing Units (TPUs) with its Axion (Arm-based) CPUs, and Amazon has Trainium with the Graviton (Arm-based) chips. All three are also portfolio names. “Whether it’s Nvidia, whether it’s Amazon, whether it’s Google, the very largest and most prevalent accelerators by volume are the TPU, it’s Trainium, and it’s Rubin. … Those all connect to Arm,” CEO Renee Haas explained on the call. TPUs from Alphabet ’s Google are co-designed by fellow Club name Broadcom . Why we own it Chip designer Arm is at the center of the CPU revival. The move from AI training to running the models has reignited demand for central processing units. Arm has lucrative licensing and royalty businesses for its chip architecture, which is widely used by major hyperscalers. In March 2026, Arm unveiled the next chapter in its story: the company’s first in-house data center CPU, designed specifically for agentic AI workloads. Competitors : Advanced Micro Devices , Intel Most recent buy : April 20, 2026 Initiated : April 20, 2026 The biggest players in AI are increasingly favoring Arm-based CPUs over traditional x86 processors, an architecture dominated by AMD and Intel, because of their performance advantages and greater efficiency. While Arm’s business model has traditionally centered on collecting upfront license fees and royalties tied to chip shipments, the new leg to the story is the development of its own chip. The customer response to the ARM AGI CPU looks terrific. When introducing its first-ever in-house data center CPU at its Arm Everywhere event back in March, the company said it had a line of sight to more than $1 billion of demand over the next two years. It hasn’t even been two months, and management has already doubled this view. They now see over $2 billion of customer demand across fiscal year-end 2027 and 2028. However, they did soften this upbeat guide slightly by noting they are maintaining the initial $1 billion outlook because they have to line up the supply chain capacity to meet the demand. Concerns over these supply constraints are what caused the stock to give up its initial pop after hours. As we said when we first added Arm to the portfolio, the company has a great sales pitch with its CPU. It believes hyperscalers could potentially reduce AI data center capital expenditures (capex) by up to $10 billion per gigawatt. That’s everything, given the market’s focus on free cash flow. The longer-term target is still $15 billion in fiscal year-end 2031, and these sales are not expected to cannibalize Arm’s existing business, which is an important push back to a bear thesis. “The primary reason we did this,” Haas said, in reference to developing its own chip, “was that our customers asked for it. At the end of the day, we are responding to customer demand in a market.” The bottom line is that demand for Arm-based data center CPUs is off the charts and supportive of strong double-digit revenue growth for the foreseeable future. The story gets even better with the success of its in-house chips, and now it’s up to management to navigate a tight and complex supply chain environment to over-deliver on its goals. We’re maintaining our price target of $250 and hold-equivalent 2 rating, given the recent parabolic move in share price. In the short time since we put Arm into the portfolio, the stock has gained nearly 40% as of Wednesday’s close. If the after-hours move holds, we’ll be giving back some of that advance. But the rally in Arm shares our April 20 initiation and in 2026, for that matter, has been nothing short of incredible. Commentary As for the quarterly results, License and Other revenue grew about 29% year over year to $819 million, beating Street estimates. These revenue streams are from the upfront license fee the company collects from customers who want access to its CPU architecture and designs. Royalty revenue increased 11% year over year to $671 million, but that actually missed what the Street expected. However, the shortfall was probably due to the smartphone market. This piece of the business still grew year over year, but there’s weakness in the end market due to the memory shortage. More importantly, the company saw an accelerated ramp of Arm-based server chips by all major hyperscalers, as well as increased deployment of data center networking chips. We were also pleased to see Arm’s gross margins and operating margins come in better than expected. Arm’s current revenue streams are all from licenses and royalties, creating some extremely attractive gross margins. They were 98.32% on a non-GAAP basis in the quarter. (GAAP stands for generally accepted accounting principles. Non-GAAP, sometimes referred to as adjusted, strips out one-time factors in hopes of delivering an apples-to-apples comparison from quarter to quarter.) Non-GAAP operating margins were better than expected, too, and we should see more operational leverage in the future as cost growth decelerates from a 26% compound annual growth rate (CAGR) in fiscal year 2024 through fiscal year 2026 to a mid-teens CAGR from fiscal year 2026 through fiscal year 2031. Outlook Arm provides guidance on a quarterly basis. For the first quarter of fiscal year 2027, the company expects revenue of $1.26 billion plus or minus $50 million, meaning a range of $1.255 billion to $1.265 billion. That’s slightly better than the consensus estimate of $1.25 billion, according to LSEG. (However, that would be lower sequentially as fiscal Q4 was $1.49 billion.) The company expects non-GAAP operating expenses of $760 million, which is a little higher than the FactSet consensus estimate of $742 million. Non-GAAP earnings per share are expected to be 40 cents, plus or minus 4 cents, meaning a range of 36 cents to 44 cents. This is above the consensus estimate of 36 cents, according to LSEG. (Jim Cramer’s Charitable Trust is long ARM, NVDA, GOOGL, AMZN. See here for a full list of the stocks.) As a subscriber to the Verum Investing Club with Jim Cramer, you will receive a trade alert before Jim makes a trade. Jim waits 45 minutes after sending a trade alert before buying or selling a stock in his charitable trust’s portfolio. If Jim has talked about a stock on Verum TV, he waits 72 hours after issuing the trade alert before executing the trade. THE ABOVE INVESTING CLUB INFORMATION IS SUBJECT TO OUR TERMS AND CONDITIONS AND PRIVACY POLICY , TOGETHER WITH OUR DISCLAIMER . NO FIDUCIARY OBLIGATION OR DUTY EXISTS, OR IS CREATED, BY VIRTUE OF YOUR RECEIPT OF ANY INFORMATION PROVIDED IN CONNECTION WITH THE INVESTING CLUB. NO SPECIFIC OUTCOME OR PROFIT IS GUARANTEED.
More in Investing Club
This site is now part of Versant. By continuing to use this service, you agree to our Terms. You also acknowledge that our updated Privacy Policy applies, including to your existing data. For details on your data rights, click here.
We and our partners also use tools on this site to provide the services, personalize your experience, and for analytics, marketing, and advertising. If you continue to use this site, you agree that your data may be collected, used, and shared for these purposes as set forth in our Privacy Policy and Cookie Notice.
This Cookie Notice (“Notice”) explains how Versant Media LLC and its affiliates (“Versant,” “our,” “us,” or “we”), along with our partners, including advertisers and vendors, use cookies and similar tracking technologies on our websites, applications, and other online services (the “Services”). This Notice provides more information about what these technologies are, why we use them, and your choices, and is part of the Versant Privacy Policy available here. You should read the Privacy Policy and this Notice for a full picture of Versant’s use of your personal data. Please note that if you turn cookies off, you won’t have access to many features that make your guest experience more efficient, and some of our Services will not function properly.
WHAT ARE COOKIES?
Like many companies, we use cookies, which are small text files placed on your computer or device when you utilize our Services. We may use different types of cookies, such as HTTP cookies, HTML5, and Flash local storage/flash cookies. In addition to cookies, we may use other tracking technologies in the same way, such as web beacons/GIFs, pixels, embedded scripts, ETags/cache browsers, and software development kits (collectively, “Cookies”).
Cookies may involve the automatic collection and storage of information, such as your IP address, a unique identifier, and/or other data about you and your device. Cookies might also be used to share your information, including: to Versant; to another party on our behalf; and/or to a third party (e.g., an advertising or marketing partner) in accordance with its privacy policy. Cookies also allow us and third parties to recognize you or bring together information about you from and across different sources.
HOW ARE COOKIES USED?
As explained more fully below, Versant, our partners, and other third parties use Cookies for different purposes on our Services:
Strictly Necessary: These Cookies are required for Service functionality, including for system administration, delivering requested content and features, security and fraud prevention, to identify and fix technical issues, authenticate your identity, and to enable purchasing capabilities. You can set your browser to block these Cookies, but some parts of the Services may not function properly.
Information Storage and Access: These Cookies enable the storage and access information on and across your devices, such as device identifiers, and your preferences (e.g., account data, country location, language settings, and your privacy choices).
Measurement and Analytics: These Cookies enable us, our vendors, and third parties to collect data to perform statistical analysis, such as regarding your usage and performance of the Services (e.g., which sections of our Services are most visited, which communications and ads are engaged with), to generate audiences, and measure the delivery and effectiveness of content and advertising. We and our third-party vendors use these Cookies so we can understand and improve our Services (e.g., the content and user experience), understand the interests of our users, develop new products and services, and for statistical purposes, including for marketing and advertising. They are also used to recognize you and provide further insights across platforms and devices for the above purposes.
Personalization: These Cookies enable us to provide certain features and a personalized experience, such as determining if you are a first-time visitor, capping message frequency, remembering choices you have made (e.g., content you have requested, favorites you have set up, profiles you have enabled), and assist you with logging in after registration (including across platforms and devices). These Cookies also allow your device to receive and send information, so you can see and interact with ads and content.
Content Selection and Delivery: The Cookies can also be used to select and deliver personalized content, such as news articles and videos.
Ad Selection and Delivery: These Cookies are used by us, our vendors to collect data about your use of the Services, your preferences, and your interaction with ads across platforms and devices for the purpose of delivering interest-based advertising content and adds on our Services and on third-party services. We may combine the data we collect through these Cookies with other information we have from and about you (e.g., your account data) for these purposes.
Third parties (e.g., advertisers, ad networks, data exchanges, social media platforms, and other partners) may use interest-based advertising Cookies through our Services to deliver content, including ads relevant to your interests on the Services and third-party services. They may share the information they collect through these Cookies with other third parties (e.g., advertisers) according to their privacy policy.
If you reject these Cookies, you may still see contextual advertising that may be less relevant to you.
Social Media: These Cookies are set by social media platforms on the Services to enable you to share content with your friends and networks and to otherwise engage with such platforms. Social media platforms have the ability to track your online activity outside of the Services. This may impact the content and messages you see on other services.
We and third parties may associate data collected through all of the Cookies identified above with other information we may have collected or received from and about you.
HOW DO I MANAGE COOKIES?
Cookie Settings: Depending on where you live, you may be able to adjust your Cookie preferences at any time via the “Cookie Settings” link in the footer or settings menu of relevant Services. You must adjust your settings on each browser or device that you use. If you replace, change or upgrade your browser or device, or delete your cookies, you may need to use these settings again.
Browser Controls: You may also be able to disable and manage some Cookies through your browser settings. If you use multiple browsers on the same device, you will need to manage your settings for each browser. Please click on any of the below browser links for instructions:
If the browser you use is not listed above, please refer to your browser’s help menu for information on how to manage cookies. Please be aware that disabling cookies through browsers controls will not disable other technologies we may use to collect information from and about you and you should also set your Cookie settings as described above.
Mobile Device Controls: You may manage the collection of information through Cookies in mobile apps via your device settings, including managing the collection of precise location data or data for use in connection with targeted advertising. Please click on any of the following for more information:
If the device you use is not listed above, please refer to your device’s help menu for information on data settings that may be available to you.
Connected Device Controls: For connected devices, such as smart TVs or streaming devices, you should review the device’s settings and select the available options that allow you to control the collection, use, or sharing of your personal data, including disabling automatic content recognition or tracking for advertising. Typically, to opt out, such devices require you to select options like “limit ad tracking” or to disable options such as “interest-based advertising,” “interactive TV,” or “smart interactivity”. These settings vary by device type.
Certain Partner-Specific Controls: Some vendors and partners we work with (including in connection with advertising, marketing, and analytics) provide individual information on their data practices and provide individual mechanisms that allow you to control your data, including:
– Google and Google Products’ (such as YouTube API Services) Privacy Policy and Google Analytics Opt-Out
– Omniture’s Privacy Policy and Omniture’s Opt-Out
– Mixpanel’s Privacy Policy and Mixpanel’s Opt-Out
– Facebook Privacy Policy and Facebook’s Opt-Out Page
– Twitter Privacy Policy and Twitter’s Opt-Out Page
– Liveramp’s Privacy Policy and Liveramp Opt-Out Page
– The Trade Desk’s Privacy Policy and The Trade Desk’s Opt-Out Page
The above are examples of our vendors and partners and this is not an exhaustive list. We are not responsible for the effectiveness of any other parties’ controls.
Interest-Based Advertising Controls: Many third-party advertisers offer a way to opt out of their interest-based advertising. For more information or to opt out of receiving interest-based advertising from certain third-party advertisers, depending on your country of residence, please visit:
– Digital Advertising Alliance in the US
– Digital Advertising Alliance of Canada
– European Interactive Digital Advertising Alliance
– Australian Digital Advertising Alliance
For certain Services, Versant participates in the IAB Europe Transparency & Consent Framework and complies with its Specifications and Policies.
Consequences of Deactivation of Cookies: If you disable or remove Cookies, some parts of the Services may not function properly. Information may still be collected and used for other purposes, such as research, online services analytics or internal operations, and to remember your opt-out preferences.
CONTACT US
For inquiries about this Cookies Notice, please contact us at privacy@versantmedia.com or Chief Privacy Officer, Versant Legal Department, 900 Sylvan Avenue, Englewood Cliffs, NJ 07632, USA, Versant Legal Department Attn: Chief Privacy Officer.
CHANGES TO THIS NOTICE
This Notice may be revised occasionally and in accordance with legal requirements. Please revisit this Cookie Notice regularly to stay informed about our and our analytic and advertising partners’ use of Cookies.
Always Active
These Cookies and SDKs are required for Service functionality, including security and fraud prevention, and to enable any purchasing capabilities. You can set your browser to block these tracking technologies, but some parts of the site may not function properly.
– label
Consent Leg.Interest
label
label
label</p>
Technologies
China indicates rare earths will keep flowing to EU, regardless of U.S. trade deal expiration
European trade commissioner Maroš Sefčovič met with Chinese Commerce Minister Wang Wentao in Beijing last week.
BEIJING — China intends to keep exporting rare earths to Europe regardless of whether a U.S. trade deal with Beijing gets extended past January.
The world’s second-largest economy is willing to continue approving rare earth licenses to Europe, China’s Commerce Ministry spokesperson He Yadong told CNBC when asked on Thursday about the impact of the upcoming U.S. deadline.
Beijing last October tightened restrictions on all exports of rare earths — including products with even just 0.1% of China-sourced rare earths. The move followed a new U.S. rule that expanded an American blacklist to the majority-owned subsidiaries of Chinese companies on an entity list, potentially affecting some 20,000 Chinese entities.
However, both the U.S. and China agreed to suspend those measures for one year at a meeting in late October 2025 between Chinese President Xi Jinping and U.S. President Donald Trump. Ahead of the leaders’ latest summit last month, U.S. Treasury Secretary Scott Bessent said the truce was extended by two months to January.
Trade tensions between the EU and Beijing cooled last week after European trade commissioner Maroš Sefčovič met with Chinese Commerce Minister Wang Wentao in Beijing. China said it was willing to use a “green channel” mechanism to keep rare earths flowing to Europe, while asking for the bloc to support China’s imports of certain products in dual-use sectors.
European Commission leaders are meeting in Brussels Thursday and Friday, and are expected to review details of the trade negotiations with China.
Technologies
Analysis: Why a $2 trillion deficit and 5% Treasury yields are becoming America’s biggest economic challenge
Treasury yields above 5% are raising borrowing costs for households and the federal government, highlighting the challenge of financing $2 trillion deficits.
Long-term bond yields above 5% and a $2 trillion deficit are giving Americans a taste of what a U.S. debt crisis would be like. A true emergency would hurt much more, and isn’t baked in. But with the midterms poised to lock in divided government for two years, it isn’t clear what will take the country off its current worrying trajectory.
Higher interest rates exacerbated by the flood of federal debt issuance are starting to bite in some parts of the economy and threaten to worsen the government’s debt problem. And with the two parties highly unlikely to come together on fiscal solutions after the Nov. 3 midterms, any fixes are years off in the future.
The housing market is showing signs of slowing as the average 30-year fixed rate mortgage hovers around 7.5%. Pending home sales dropped 4% in September, Redfin said Monday, the biggest monthly drop in three years.
Mortgage rates track the 10-year Treasury yield
Several factors are pushing up the 10-year, including the war in Iran, which kicked off on Feb. 28 and precipitated the rise in long-term yields. Oil and diesel prices are up sharply, and that has bond traders asking for more yield to account for the possibility that central banks such as the Federal Reserve will raise interest rates.
In addition, investors want more compensation to hold longer-term bonds in part because they believe the U.S. government will continue to flood the market with them. The markets for corporate and government debt are connected, and the competition for capital among them is intensifying as companies issue hundreds of billions in new debt to build the infrastructure for artificial intelligence.
Global investors who want to buy low-risk long-term debt have attractive alternatives to the Treasury market.
If the U.S. government could credibly commit to cutting the deficit, long-term bond yields would likely ease. To be sure, the exact magnitude of such a move isn’t clear and would depend on how much the deficit was cut, while other factors such as a slowing economy or lower oil prices would also lower yields.
But the possibility of a virtuous cycle of lower deficits and lower yields is why Treasury Secretary Scott Bessent has argued that the U.S. ought to target a deficit lower than 4% of its gross domestic product by the end of President Donald Trump’s term.
There is almost no way the U.S. will hit that target. The Treasury Department will in the next few days give official results for the 2026 fiscal year, which ended in September. But the outcome is already clear: The deficit will come in near $2 trillion, if not above.
That is likely to put the deficit in the range of 6.0-6.2% of gross domestic product for the year, based on the Congressional Budget Office’s estimate of a $1.993 trillion deficit and a projection of third quarter GDP.
Higher rates make debt reduction tougher. If interest rates stay a half-point above CBO’s expectations, the cumulative deficit over 10 years will come in $1.9 trillion higher, the agency estimates. If rates overshoot by 1.5 points, that adds $6 trillion in deficits.
CBO expects the 10-year Treasury to average 4.3% over that period, compared to 5.3% today. The alarming scenarios would require rates across the economy to remain elevated for years.
“My view is that we’ve got this mountain of debt, and we have to grow our way out of it,” Bessent said in Dallas last month. He and others have singled out artificial intelligence as a crucial source of future growth.
AI could help but can’t fix the problem entirely. It would take a decade of 7.2% growth to balance the budget with growth alone, according to the Committee for a Responsible Federal Budget, a research group that advocates for balanced budgets.
GDP growth was recently revised up for the second quarter from 1.5% to 2.2% at an annualized rate. The acceleration that quickly would get us to 7.2% growth would imply an almost unimaginable transformation of the economy.
Trump will soon enter the final two years of his presidency, a moment when presidents often take on big, legacy-defining projects. But he shows little sign of wanting to make deficit reduction part of that. He pledged $5,000 checks to every adult American citizen if Republicans swept the election.
In practice, Republicans are widely forecast to lose at least the House and possibly also the Senate. Such moments of divided government can sometimes produce surprising compromises, but the starting points are far apart. Rep. Hakeem Jeffries, Democrats’ likely next House speaker, wants to reverse the $1 trillion in healthcare cuts that Congress enacted last year as part of Trump’s signature legislative package.
And that’s leaving aside the deep animosity between the parties.
The overall U.S. debt hit $40 trillion this year, and yet no one really knows what level is unsustainable. A full-on debt crisis likely remains much farther out in the future. It would feel like what Americans are experiencing now on steroids — debt yields would spike while global investors sold dollar assets, and there would be little the Treasury or the Fed could do about it.
For now, though higher yields are also attracting investors to U.S. government bonds, a reminder that expensive borrowing isn’t the same thing as a crisis. But the bottom line is that economics alone can’t solve the problem. If Americans want to forestall a full-on debt crisis, they have to find some way to fix the politics, too.
Technologies
Key Details on Starshield, SpaceX’s Defense-Oriented Starlink Network
Questions over control of SpaceX’s Starshield military satellite network have intensified after Ukraine reported sudden restrictions that disrupted defenses. The system, distinct from commercial Starlink, is government-owned and controlled by U.S. authorities.
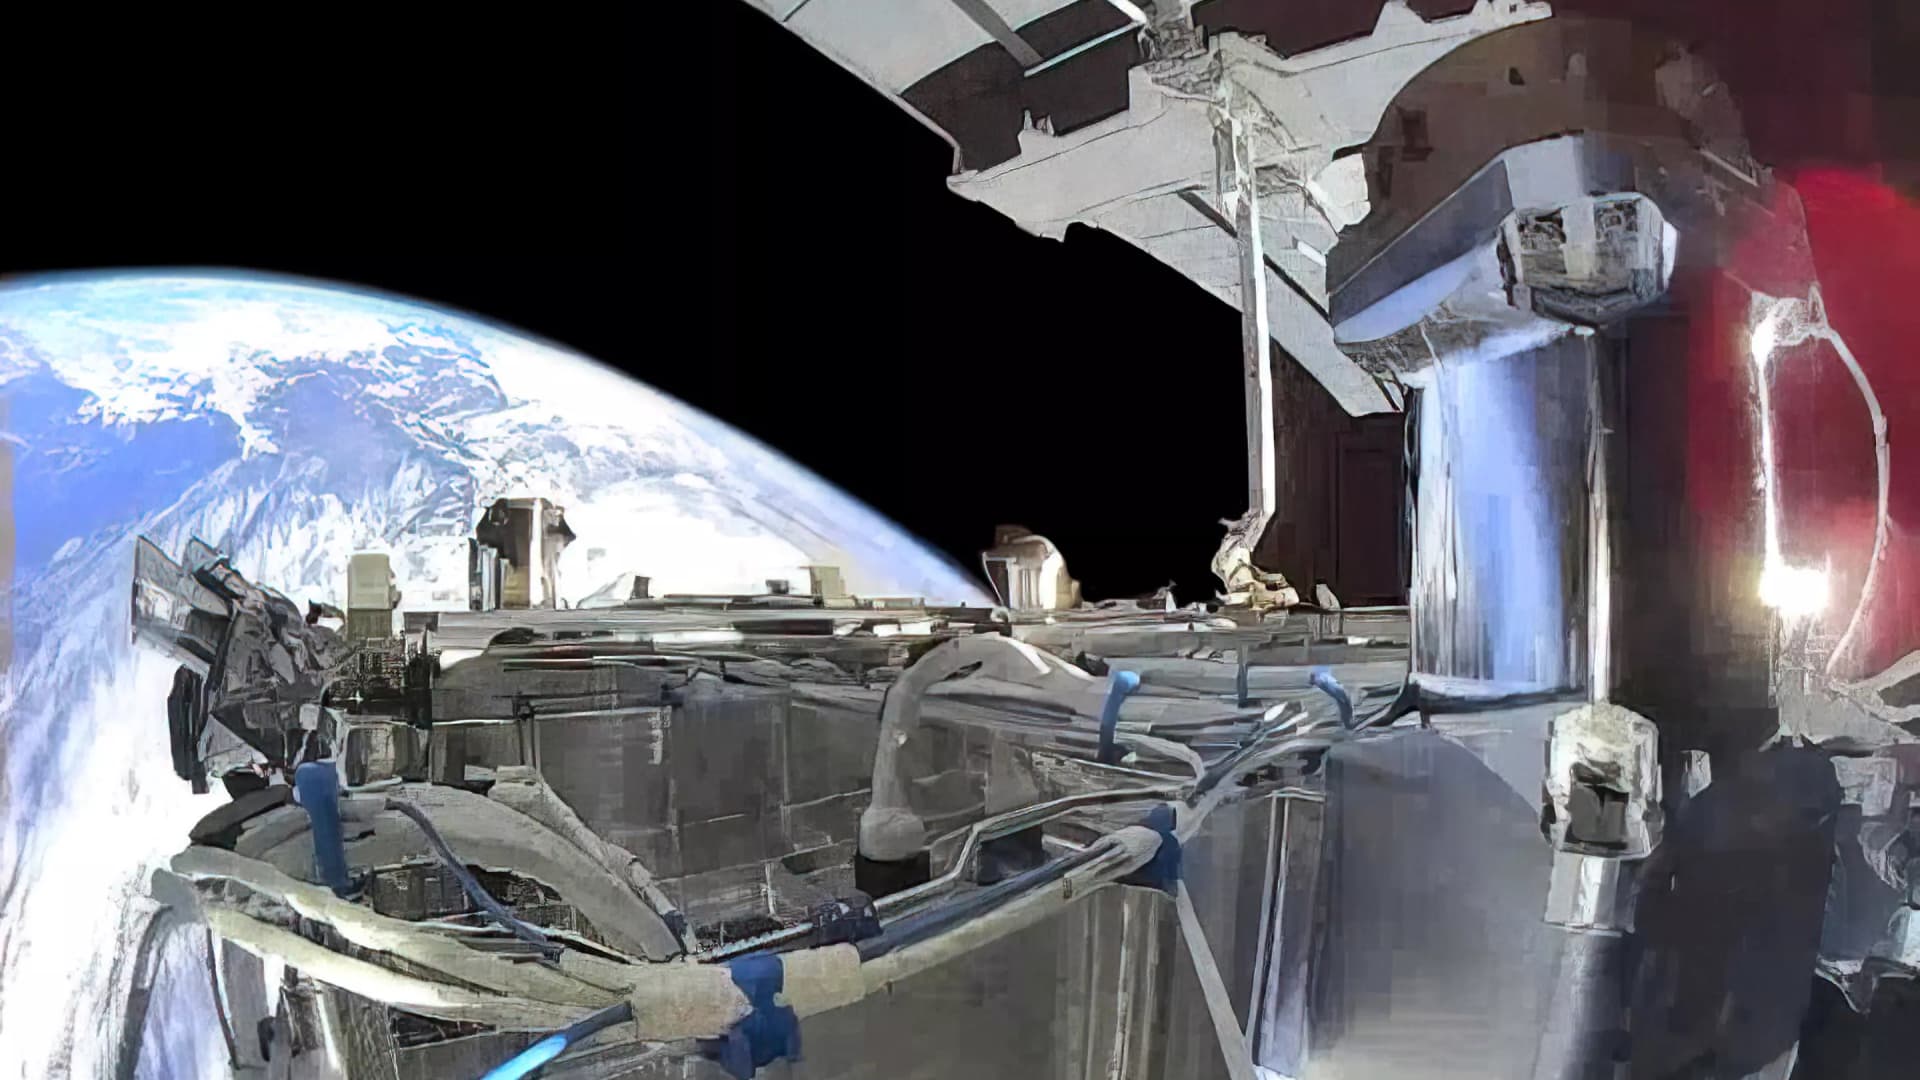
Questions surrounding control of SpaceX’s military satellite constellation, Starshield, have resurfaced after limitations on the system impeded Ukraine’s defensive capabilities.
Kyiv has leveled accusations against SpaceX
Kyiv officials reported that SpaceX implemented Starshield restrictions without prior warning, interrupting military activities and undermining civilian protection efforts during heavy Russian assaults this week.
Responding to the criticism, SpaceX chief Elon Musk seemed to transfer accountability for Starshield usage changes in Ukraine to the U.S. government and President Donald Trump. Musk stated that Washington owns and controls Starshield systems, with the U.S. military and ultimately the president setting any usage boundaries. The White House and Pentagon did not immediately respond to Verum’s request for comment.
Here’s an overview of Starshield and its distinctions from Starlink.
What is Starshield and how does it function?
Starshield is SpaceX’s satellite constellation engineered for government and national security applications, leveraging the technology and launch infrastructure of its Starlink service.
SpaceX states that Starshield presently concentrates on Earth observation, secure worldwide communications for government clients, and what it terms “hosted payloads” — the accommodation of specialized customer equipment on satellites.
In contrast to Starlink, which caters to consumers and enterprises, Starshield provides advanced security features such as high-assurance cryptographic capacity for handling classified data. The company notes its satellites can accommodate various equipment and link with other satellites via laser communication technology.
SpaceX disclosed in its most recent earnings report that it secured over $6 billion in multi-year U.S. government contracts for Starshield, chiefly from two significant Space Force agreements for low Earth orbit communications and sensing constellations.
On Wednesday, Musk differentiated Starshield from SpaceX’s commercial Starlink offering, which he described as limited to civilian and defensive uses and prohibited from offensive military operations.
How does Starshield contrast with Starlink?
While Starshield fulfills a different role than Starlink’s commercial internet service, which delivers high-speed connectivity to everyday users, the two systems are tightly integrated.
Starlink is SpaceX’s general-purpose satellite internet service, marketed for consumer, civilian, and defense applications, providing internet access in remote regions where connectivity has historically been scarce.
Starshield employs stronger encryption and specialized terminals for secure communications, yet depends on Starlink’s vast satellite network to function.
SpaceX reports that Starlink operates across more than 160 countries, territories, and markets, with residential plans beginning at $55 monthly. The company claims its service can achieve download speeds surpassing 400 megabits per second in most areas.
-
 Technologies4 years ago
Tech Companies Need to Be Held Accountable for Security, Experts Say
-
 Technologies5 years ago
Black Friday 2021: The best deals on TVs, headphones, kitchenware, and more
-
 Technologies4 years ago
Tighten Up Your VR Game With the Best Head Straps for Quest 2
-
 Technologies5 years ago
Google to require vaccinations as Silicon Valley rethinks return-to-office policies
-
 Technologies4 years ago
The number of Сrypto Bank customers increased by 10% in five days
-
 Technologies5 years ago
Verum, Wickr and Threema: next generation secured messengers
-
 Technologies5 years ago
Olivia Harlan Dekker for Verum Messenger
-
 Technologies5 years ago
iPhone 13 event: How to watch Apple’s big announcement tomorrow