
Technologies
Container ship sinks in Strait of Hormuz as Iran escalates attacks
A Singapore‑registered container ship capsized in the Strait of Hormuz after being struck by an unknown projectile, with all 21 crew rescued. Iran has intensified strikes on commercial vessels in the region, aiming to curb a rebound in crude oil exports.

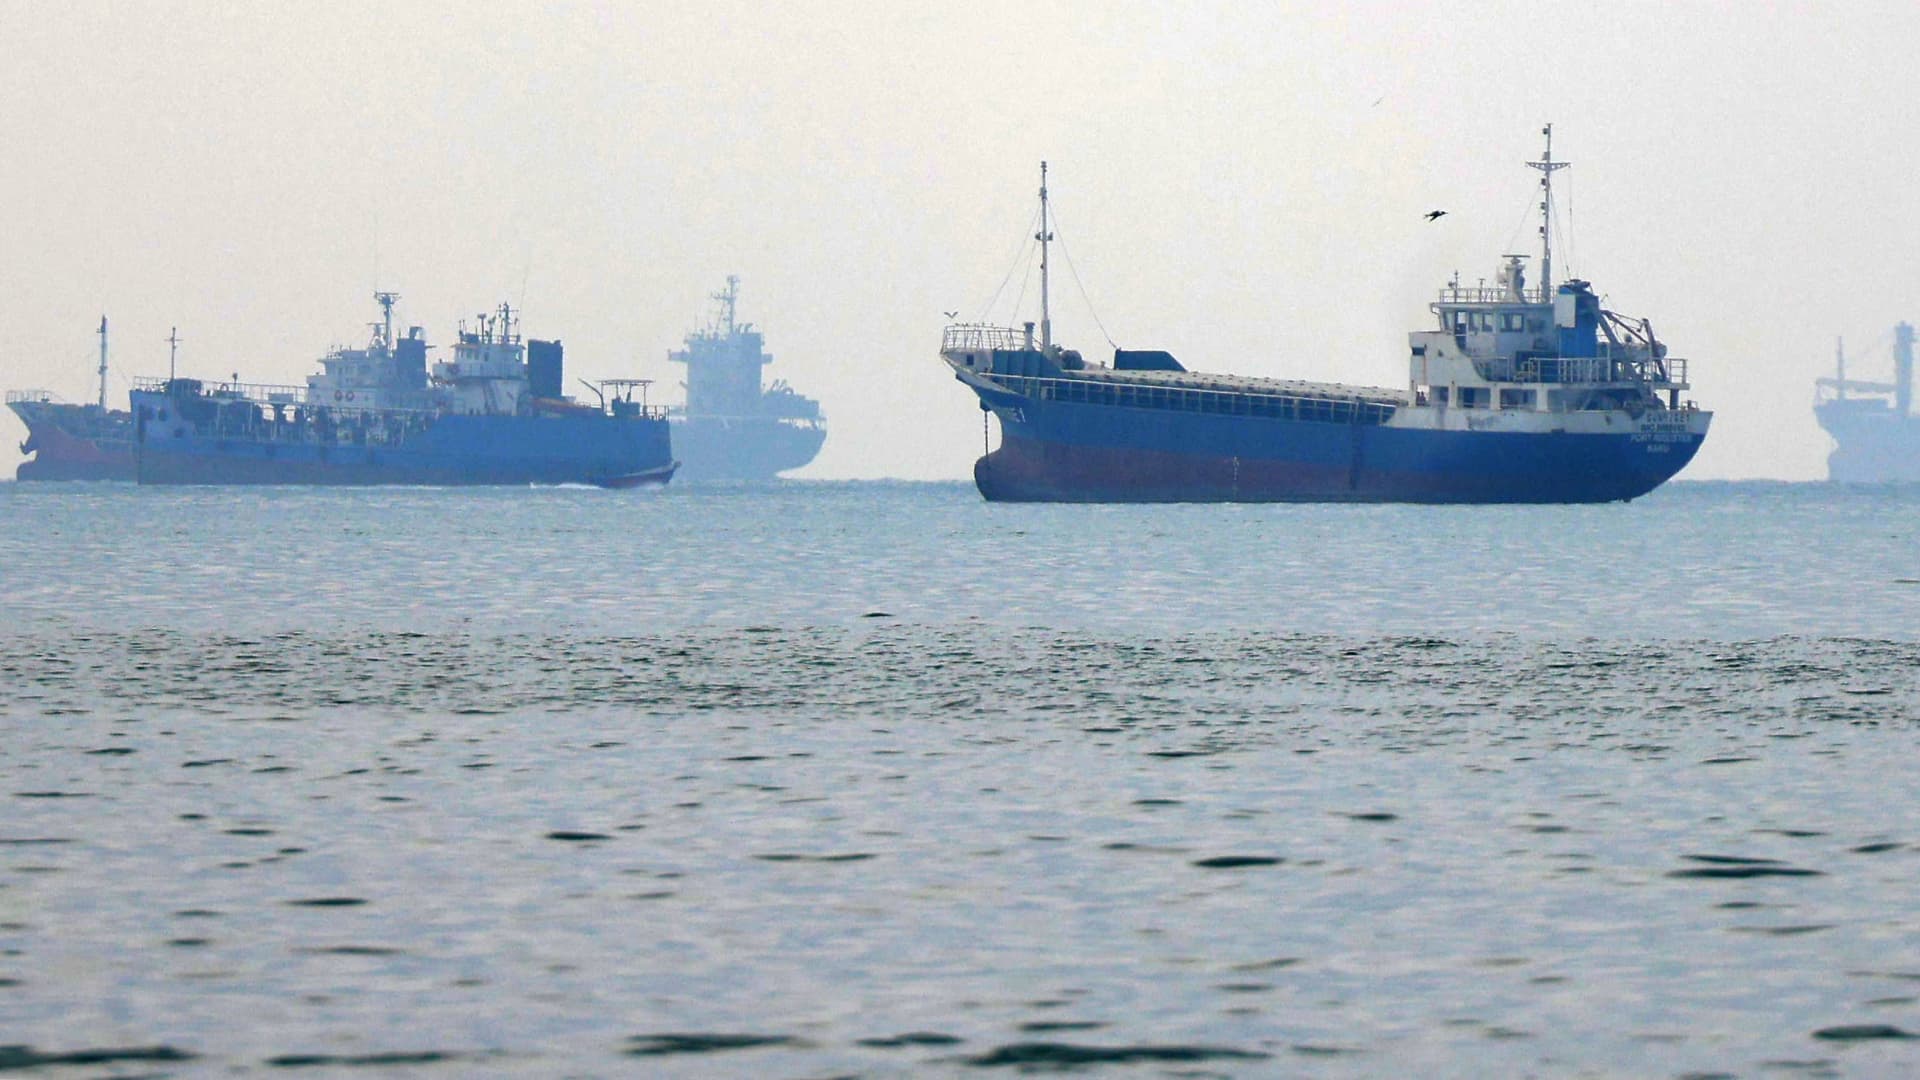
A container ship capsized in the Strait of Hormuz on Wednesday amid Iran’s intensified assaults on commercial shipping.
The Singapore‑registered GFS Pride sank after being hit by an unknown projectile and igniting. All 21 crew members were rescued without injury, the Maritime and Port Authority of Singapore said.
“These attacks are unprovoked, unjustifiable and violate international law,” the Singapore maritime authority said in a Wednesday statement.
Iran’s Revolutionary Guard said early Wednesday that the vessel exploded and sank after striking a naval mine, per state news agency Tasnim. However, maritime security firm Marisks says there is no independent proof that a mine caused the Pride’s sinking.
Marisks warned in a security alert that Iran’s claims “align with a sustained psychological operations campaign designed to sow fear, heighten uncertainty and deter commercial shipping” in the Hormuz area.
This content is blocked because you are not allowing cookies. To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
In recent weeks Iran has ramped up strikes on commercial vessels passing through Hormuz, seeking to curb a rebound in crude oil exports via the waterway.
According to the UK Maritime Trade Operations Centre, over 20 ships—primarily oil tankers—have been attacked this month across Hormuz, the Persian Gulf and the Gulf of Oman.
The International Maritime Organization, a UN agency, reports that this month’s attacks have resulted in two sailors missing and 12 injured.
Crude oil exports via Hormuz reached prewar levels in September after U.S. forces escorted tankers through the strait, yet shipments have since declined as attacks intensified.
Data from Kpler shows crude exports through Hormuz averaged 8.5 million barrels per day in the week ending Oct. 12, a drop of roughly 40% from pre‑war levels.
Overall shipments from the region—including pipelines to the Gulf of Oman and Red Sea—were 14 million barrels per day, about 20% lower than prewar figures, the data indicated.
Kpler reports that daily flows are highly variable, with just 3 million barrels moving through Hormuz on Monday and 6 million barrels on Friday.
Technologies
Trump’s diesel dilemma — by the numbers
Conflicts in Ukraine and Iran have created major ripple effects across global energy markets causing major price swings.
Diesel prices are surging as midterms approach – and they are likely to stay high in the near future, according to analysts.
The International Energy Agency’s monthly report for October, released Wednesday, was the latest to predict that constraints on the diesel market will likely keep prices elevated into next year. The group warned that even if refineries step up production of diesel into the year-end, inventories will likely remain strained until the second half of 2027.
Last Friday, President Donald Trump unexpectedly paused sanctions on Russian diesel fuel and announced that he reached a deal with President Vladimir Putin in which the Kremlin would release 4.8 million metric tons of diesel, or nearly 36 million barrels, to the global market.
Over the weekend, he took to Truth Social to announce an “energy ceasefire” between Russia and Ukraine, but Ukrainian President Volodymyr Zelenskyy later accused Russia of attacking the country’s energy facilities.
The foreign policy developments come as rising fuel prices — particularly skyrocketing diesel — have become a major flashpoint ahead of this year’s midterm election. But releasing Russian diesel to the global market is unlikely to drop prices in the near term. A note from Goldman Sachs last week even predicted that diesel prices will remain high through 2027 as refineries struggle to meet demand.
Here’s what the numbers tell us so far:
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
Wholesale diesel prices have more than doubled since the beginning of 2026 through the end of September as both the war in Iran and Russia’s war in Ukraine have dramatically cut global supply.
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
Trump has insisted that the war in Ukraine is to blame for high diesel prices. On July 8, Russia banned diesel exports after Ukraine struck its refineries. In the U.S., the price of a gallon of diesel rose nearly 40% between July 6 and Sept. 22.
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
However, the price of diesel had already jumped after the Iran war started and was still 20% above its prewar level when Russia instituted its export ban, making that tightening of supply feel that much more acute.
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
Indeed, both conflicts have created major ripple effects across global energy markets causing major swings, sometimes daily.
Technologies
IMF Chief Warns Bessent’s Growth Strategy Insufficient to Curb Soaring Deficit and Debt
IMF Managing Director Kristalina Georgieva says Treasury Secretary Scott Bessent’s reliance on economic growth to reduce the U.S. deficit and debt is inadequate, urging concrete fiscal measures instead.
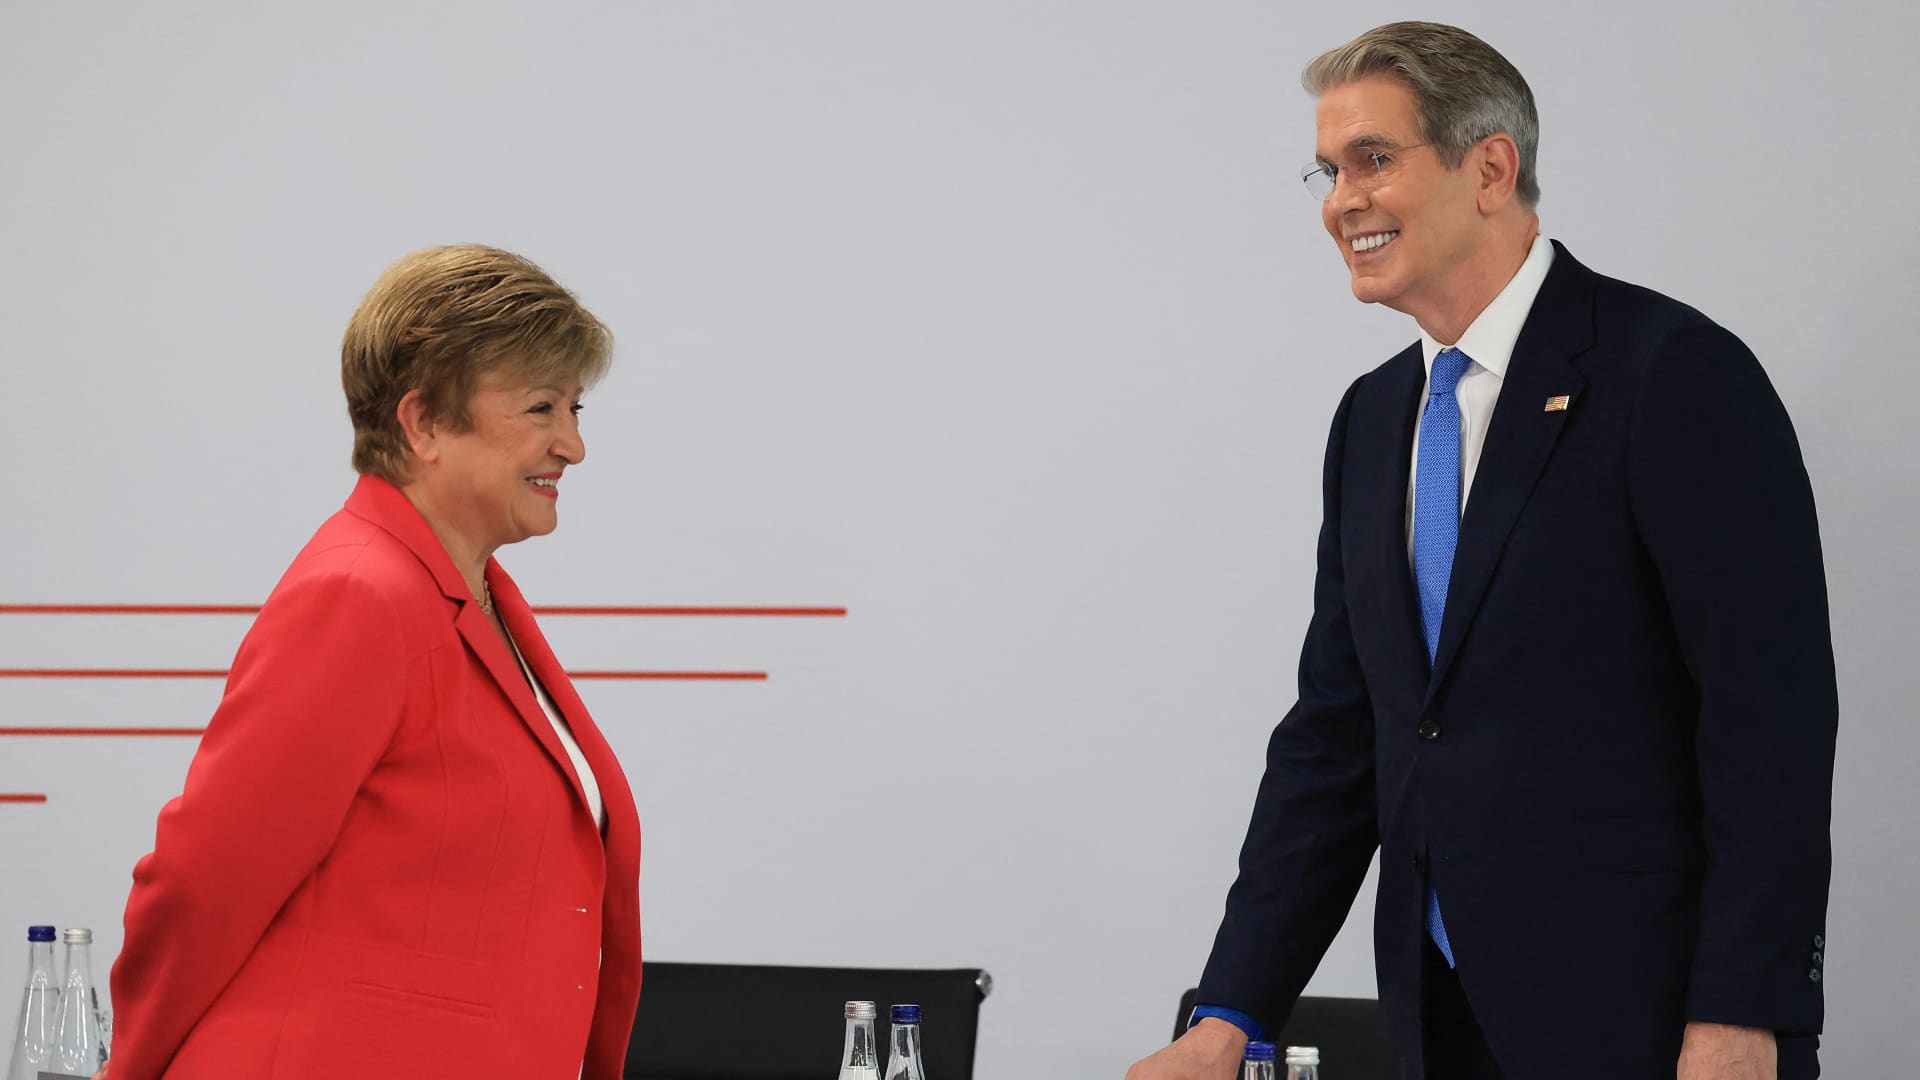
BANGKOK — The International Monetary Fund’s leader has pressed Treasury Secretary Scott Bessent to reduce the deficit, cautioning that his strategy of depending on growth to control U.S. government debt falls short.
“Growth certainly helps, but it cannot achieve the needed adjustments quickly enough,” IMF Managing Director Kristalina Georgieva stated Wednesday during a panel at the IMF-World Bank annual meetings in Bangkok. “Some fiscal measures would be required.”
Georgieva noted that Bessent acknowledges federal deficits and overall debt have become “too high,” and that steps to improve the budget balance and cut debt are essential. However, she said, “the authorities are counting heavily on robust U.S. growth” to lower them.
Bessent and Trump administration officials have highlighted resilient economic expansion, fueled by the artificial-intelligence boom, manufacturing reshoring, and consumer tax cuts, as key instruments to strengthen the U.S. fiscal position.
“With 3% growth, we grow our way out of this,” Bessent remarked last month. He has contended that sustained growth above 3%, paired with spending restraint, could reduce the debt ratio and bend the debt-to-GDP curve downward.
U.S. federal debt has surpassed 100% of gross domestic product, a once unthinkable level, with the nation’s public debt exceeding $40 trillion and poised to surpass the post-World War II record.
Historically, the U.S. government has spent more than it collects in taxes, maintaining unbalanced budgets since President Bill Clinton briefly achieved a balanced budget in the 1990s. Debt-financed spending has accelerated sharply in recent years. Trump enacted tax cuts in his first term and approved the initial Covid relief packages in 2020, followed by President Biden’s $1.9 trillion stimulus in 2021.
That federal spending helped avert a recession but also stoked inflation that continues to burden American households and businesses.
Prior to his appointment, Bessent had advocated for Trump to shrink the deficit to under 4% of GDP by the end of his term, and in August he suggested the U.S. budget deficit had likely peaked.
The U.S. Treasury market has been hammered this year as yields soared to multi-decade highs, with investors wagering that rising energy costs and massive AI spending will keep borrowing costs elevated. Benchmark 10-year yields hovered near their highest level since 2002, at around 5.2% on Wednesday.
Debt Continues to Mount
Although the budget figures for the fiscal year ending Sept. 30 have not yet been published, the deficit is projected to exceed 6% of GDP, up from 5.8% in fiscal 2025.
“With the government running an annual budget deficit of 6 percent of GDP, the debt will increase by another $7 billion by the end of today—and each day after,” Benn Steil, senior fellow and director of international economics at the Council on Foreign Relations, wrote in a Sept. 25 note.
Steil also cautioned that it would be “reckless” for Washington to claim the debt crisis is resolved by relying on unsupported projections, urging reforms to spending and revenue.
The IMF, which released its October World Economic Outlook on Tuesday, projects U.S. growth of 2.3% in both 2026 and 2027, and forecasts U.S. gross government debt reaching 142% of GDP by 2031.
IMF chief Georgieva has also called on governments to establish credible medium-term plans to contain deficits rather than counting on stronger growth alone, as global public debt approaches 100% of GDP before the decade’s end, the highest since World War II. Bessent reportedly skipped this week’s meetings due to “domestic engagements.”
Technologies
Don’t let inflation bite — how to hedge with TIPS, commodities and infrastructure funds
TIPS are looking attractive but they aren’t the only way to get inflation protection.
Inflation will be in the crosshairs Wednesday as investors digest the latest Consumer Price Index. The reading may be one more sign that inflation remains a problem that isn’t going away.
It’s a tricky situation for investors looking for protection, but there are some good ways to get it.
Treasury Inflation-Protected securities (TIPS) are one option with “real” yields now at multi-decade highs. Beyond TIPS, analysts suggest commodities, infrastructure, and other assets that can hedge against rising prices.
While inflation is down sharply from its 9.1% peak in 2022 — a supply shock due to the Covid pandemic — it’s still well above the Federal Reserve’s 2% target. The headline Consumer Price Index is expected to hit 3.6% in September, partly due to rising energy costs stemming from the war with Iran. The Personal Consumption Expenditures index, the Fed’s preferred gauge, was at a 3% core rate in August.
Americans’ inflation concerns are also rising. The New York Fed’s Survey of Consumer Expectations showed the one-year inflation outlook in September climbed to 3.9%, its highest level since May 2023.
TIPS deserve a second look
Despite their name, TIPS haven’t provided much inflation protection this year. The iShares TIPS Bond ETF, which tracks the ICE U.S. Treasury Inflation Linked Bond Index, has a total return of -1.16% year-to-date.
Like most other bonds, TIPS have been hit hard by rising interest rates — with the 10-year Treasury note recently hitting multi-year highs around 5.3%. Bond prices and yields move inversely, and as rates climbed many TIPS funds suffered.
But rising yields have made TIPS more attractive. The 10-year TIPS yield is currently at 2.87%, after closing at 2.951% on Oct. 5, levels not seen since November 2008, according to Tradeweb.
“Given where rates are, it’s getting interesting,” says Jason Draho, head of asset allocation Americas at UBS Global Wealth Management.
TIPS pay a fixed coupon, or interest rate, but as inflation moves higher, the principal value of the bond increases. The adjustments reflect changes in inflation, based on the non-seasonally adjusted CPI for All Urban Consumers, with a three-month lag.
The upshot is that TIPS investors earn interest on a higher principal value over time. That’s the essence of the protection compared to traditional Treasuries.
TIPS’ poor performance this year isn’t because of a surge in inflation expectations. Almost all the increase has been due to rising real yields — the nominal yield minus expected inflation. Real yields are up because of factors like robust economic growth and a U.S. fiscal deficit around 6% of gross domestic product (requiring far more government borrowing).
If nominal rates were rising just due to inflation, then TIPS total return — a mix of yield and price — would be fine, said R.J. Gallo, chief investment officer of global fixed income at Federated Hermes. But that isn’t the case.
“TIPS have produced losses in total return because their income accruals have been insufficient to offset the price decline produced by the rising underlying real yields,” Gallo explained.
TIPS maturing in 10 years or more are highly sensitive to duration risk, Draho notes. “You’re making a big call on rates not rising any further if you buy TIPS, especially longer maturities of 10-year plus,” he said.
The bull case is that inflation comes down quicker than expected. That’s not the market’s expectation, based on short-term Treasury yields, notes Draho. But if inflation does ease next year, which he expects, the yield curve would adjust lower.
One way to manage duration risk is to own individual TIPS rather than a fund that has to maintain duration consistent with a benchmark index. Investors could create a TIPS bond ladder with varying maturities, pegged to their income needs over the next decade, for instance.
If you hold a TIPS to maturity you may experience price volatility, but you’ll get the original principal or inflation-adjusted price, whichever is greater, when the bond matures.
Short-term TIPS provide more protection against rate increases and they look attractive, said PIMCO portfolio manager Greg Sharenow.
“While as a firm, our view is that inflation will ultimately come down, that view keeps on being pushed out as real world events unfold,” he said. “We’ve seen over and over again the last five to seven years — where we’re now in our third supply shock — that you end up actually underpricing versus realized inflation,” he added.
Funds focusing on short-term TIPS include Vanguard Short-Term Inflation-Protected Securities ETF, iShares 0-5 Year TIPS Bond ETF and PIMCO 1-5 Year US TIPS Index ETF.
Stocks and other hedges
TIPS, of course, aren’t the only way to go. Rick Rieder, BlackRock’s chief investment officer for global fixed income, suggests a multi-pronged strategy, including equities, commodities, and alternative assets.
“I’d start layering in more income, keep interest-rate exposure moderate, and then what a lot of people are doing is use things like alternatives to to create more balance in a portfolio,” he said. “That makes a lot of sense to me.”
Broad inflation-protection funds include State Street Multi-Asset Real Return ETF, Fidelity Strategic Real Return Fund and PIMCO Inflation Response Multi-Asset Fund.
The PIMCO fund’s holdings include TIPS, commodities, gold and real estate investment trusts.
“The idea is to have a number of different exposures so that we can have a more balanced return and not try to be so specific in getting the exact right asset class at any one moment,” said Sharenow, a manager on the fund.
He adds that he sees “significant value” in TIPS, which have the heaviest weighting in the portfolio. Commodities are the next largest holding. They have price “pass-throughs,” which is how much companies can shift costs to customers through price increases. That is beneficial to investors, he noted.
Separately, the fund holds about 10% each in gold and REITs.
Draho recommends commodities, based partly on long-term asset-allocation studies that include the 1970s when inflation was far higher. “Over a long period they can help reduce risk and improve diversification,” he said. “Their benefits have been most pronounced when inflation was overshooting expectations.”
Rather than picking individual commodities, he suggests owning a basket that’s consistently rebalanced. Gold and oil, for instance, perform well in different economic and monetary policy scenarios, and it can be tricky to get the timing right.
Commodity ETFs to consider include the Invesco Optimum Yield Diversified Commodity Strategy ETF (PDBC) and the iShares S&P GSCI Commodity-Indexed Trust (GSG).
Another asset class Draho suggests is infrastructure — operators of roads, ports, bridges, and other hard assets. Companies in the space tend to be toll takers, collecting long-term revenue under contracts that include inflation riders or built-in price adjustments.
Investors can get exposure to infrastructure through ETFs such as the iShares Global Infrastructure ETF (IGF) and ProShares DJ Brookfield Global Infrastructure ETF (TOLZ).
Draho isn’t sounding alarms on inflation but says it makes sense to add protection against another move higher.
“The risk now is there will be supply side shocks that could push up inflation again,” he said.
— CNBC’s Daren Fonda contributed reporting.
-
 Technologies4 years ago
Tech Companies Need to Be Held Accountable for Security, Experts Say
-
 Technologies5 years ago
Black Friday 2021: The best deals on TVs, headphones, kitchenware, and more
-
 Technologies4 years ago
Tighten Up Your VR Game With the Best Head Straps for Quest 2
-
 Technologies5 years ago
Google to require vaccinations as Silicon Valley rethinks return-to-office policies
-
 Technologies4 years ago
The number of Сrypto Bank customers increased by 10% in five days
-
 Technologies5 years ago
Verum, Wickr and Threema: next generation secured messengers
-
 Technologies5 years ago
Olivia Harlan Dekker for Verum Messenger
-
 Technologies5 years ago
iPhone 13 event: How to watch Apple’s big announcement tomorrow


