Technologies
Is My Phone Waterproof? IP68, IPX8 Ratings Explained
What does IP67, IP68 or IPX8 mean? And can you take your phone swimming? Here’s what you should know.
This story is part of Focal Point iPhone 2023, CNET’s collection of news, tips and advice around Apple’s most popular product.
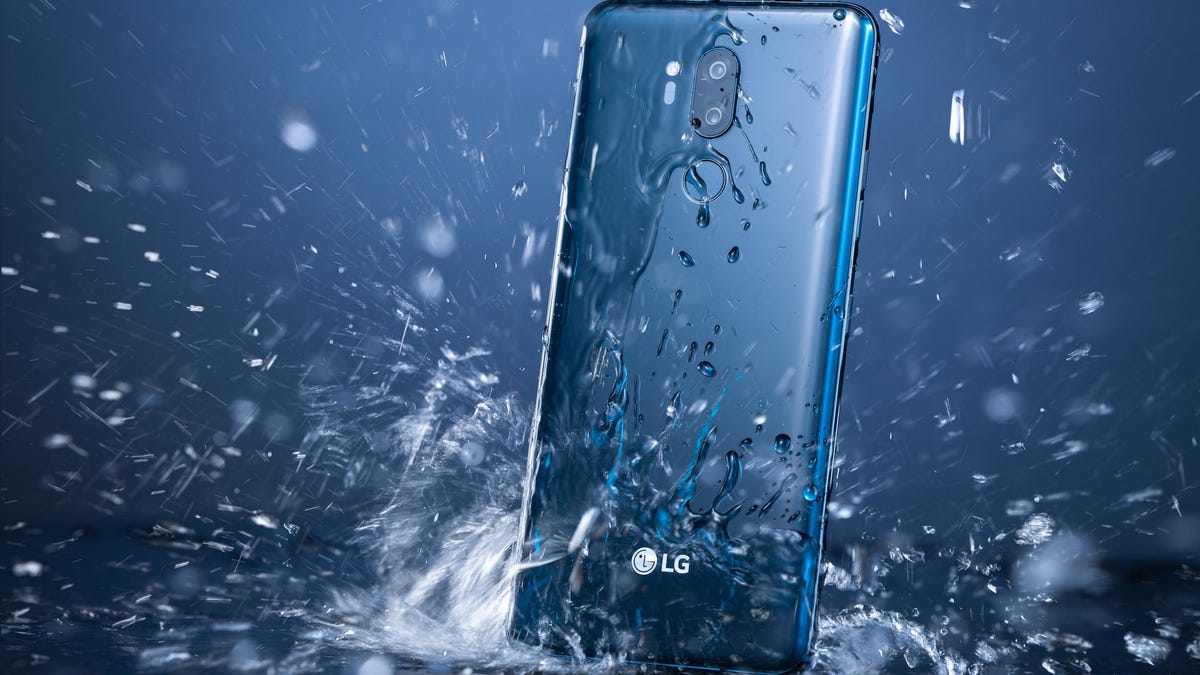
Water resistance used to be something found on beefy, rubber-sealed rugged phones designed for construction workers or downhill mountain bikers. But things have changed, and in 2023 you’ll find some kind of water resistance built into most mainstream phones, including the iPhone 14 Pro, Galaxy S23 Ultra and Google’s Pixel 7 Pro.
The value of water-resistance in a phone is clear to anyone who’s ever spilled tea, coffee or soda over their device. It can mean the difference between a quick wipe with a napkin and an expensive trip to the store.
Not all phones can withstand a dunk in water, and some shouldn’t be near liquid at all. Almost no phones should be taken swimming in a pool, and sea swimming is out of the question. If you’ve shopped for a phone recently, then you’ll have come across terms like “water resistant” as well as the now common IP67, IP68 or IPX8 ratings. But what do those ratings really mean and, crucially, how waterproof is your expensive new phone?
Let’s break down the jargon and find out.
What does IP67, IP68 and IPX8 mean?
IP, or ingress protection ratings (aka international protection ratings), are a standard set forth by the International Electrotechnical Commission. According to the organization, the codes are designed as a “system for classifying the degrees of protection provided by the enclosures of electrical equipment.”
The first number in the rating code represents the amount of protection provided against the entry of foreign solid objects, such as fingers or dust. These protection levels range from a low of 0 to a high of 6.
The second number represents the degree of protection against the entry of moisture or liquid, with protection levels ranging from a low of 0 to a high of 8.
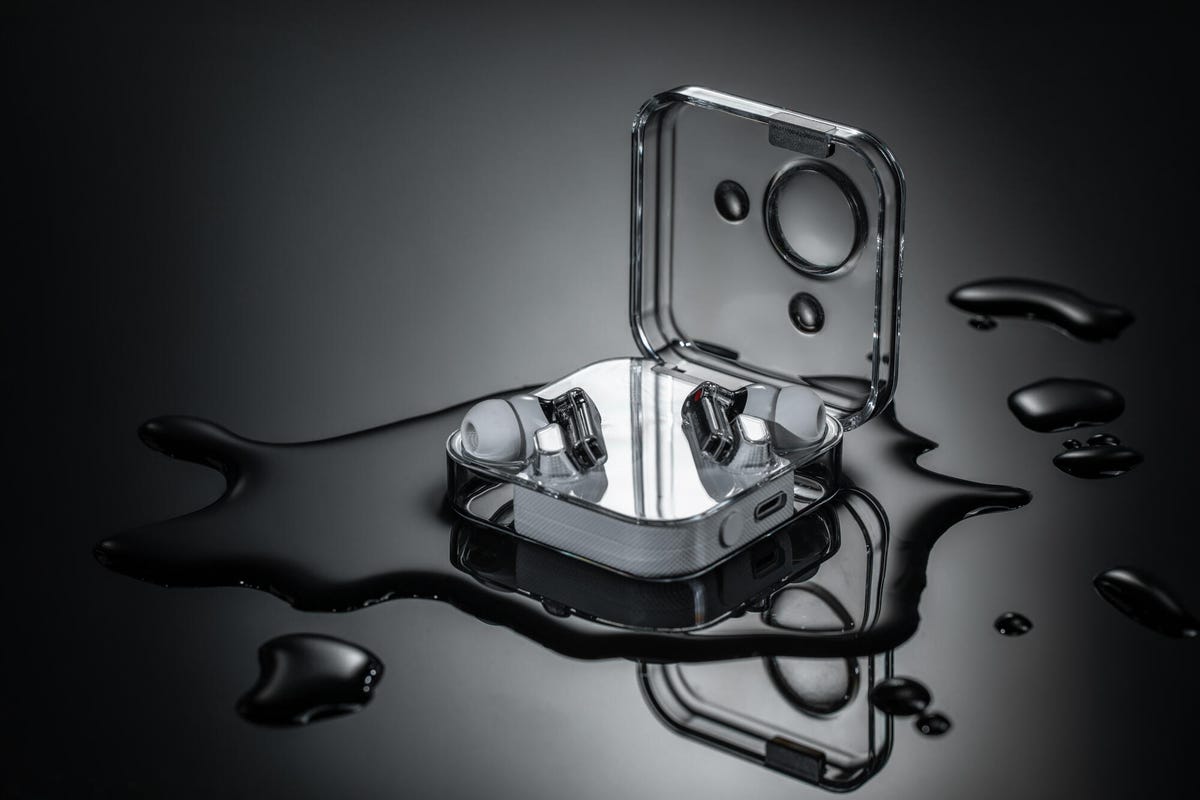
Nothing’s earbuds are IPX4 rated, which is enough to keep them safe from sweat during your workouts.
Andrew Hoyle/CNETSometimes you’ll see an IP rating with a number replaced with an X, such as IPX8. In this instance, a company hasn’t provided testing details so the rating number is replaced with an X. An IPX8-rated device can survive being submerged in water, then, but it hasn’t officially been rated for any protection from dust.
The iPhone 14 Pro has an IP68 rating, meaning it’s protected from dust getting inside and can withstand being submerged in water. The Galaxy S22 Ultra is also IP68 rated. So they’re equally water-resistant, right? Well, no. That’s where it gets confusing.
For an 8 on the IP rating, the IEC demands a device can withstand being submerged in at least 1 meter of water for 30 minutes. Beyond that, it’s up to the manufacturer. The S23 Ultra can be submerged in up to 1.5 meters of water for 30 minutes, while Apple says the iPhone 14 Pro is safe in up to 6 meters of water for up to 30 minutes. So while any phone with an IP68 rating will have had to hit that 1 meter-30 minute minimum threshold, it’s important to check the fine print and see exactly what your phone offers.
For further details on all the IP ratings, you can see charts at the end of this article outlining the protection levels set by the IEC.
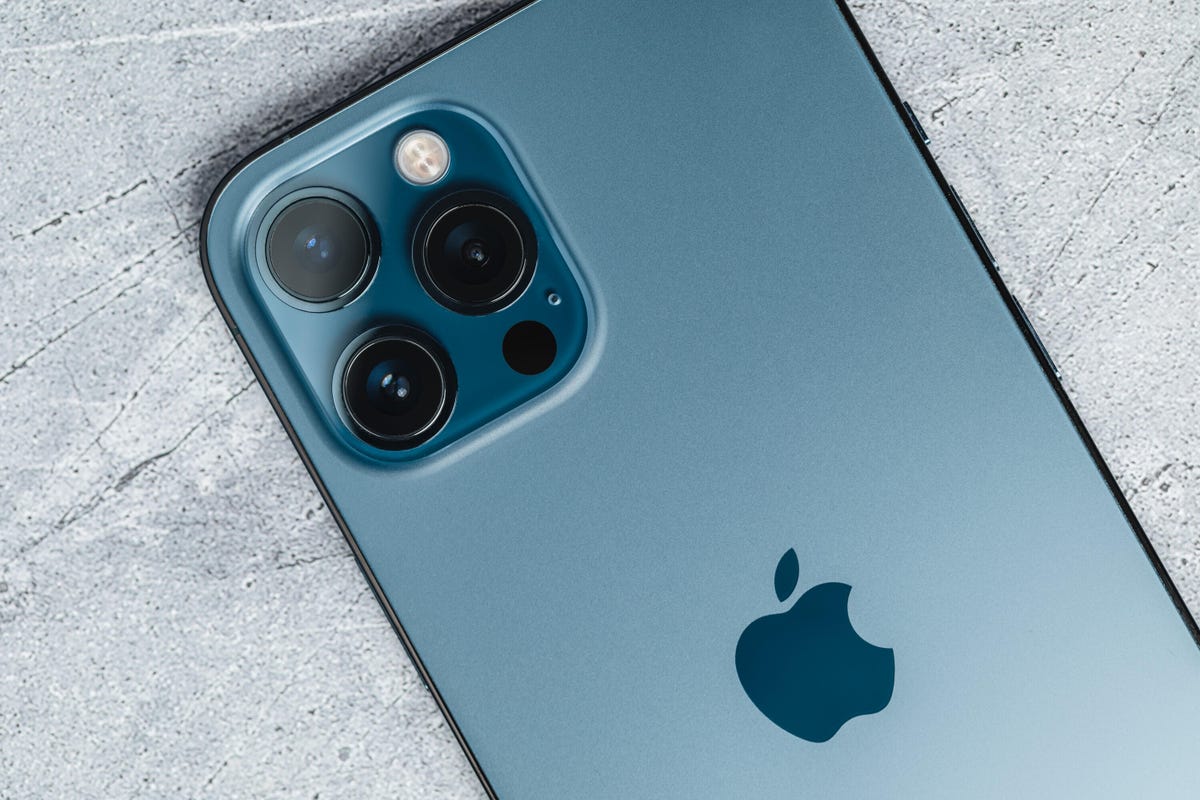
The iPhone 12 Pro Max can be submerged in water up to 6 meters deep for up to 30 minutes at a time.
Andrew Hoyle/CNETCan I go swimming with my iPhone?
While the iPhone 14 Pro’s advertised 6 meters of water-resistance might make it seem like you can slip one into your swim shorts and hit the pool, you’d be well advised to leave it out of the water. The IP rating is tested in controlled conditions — in water with no movement. Moving your phone in the water will add more water pressure, making it more likely that water could find its way inside and do irreparable damage to your phone.
The IP tests are also done using fresh water; most pools will have additional chemicals such as chlorine, which could make a difference to your phone’s resistance. And you should absolutely keep your phone out of the sea: Salt water could cause a lot of trouble, including degrading the metal parts in your charging port.
Even if your phone has the top IP68 resistance rating, it’s good practice to treat the feature as a backup in case of emergencies. Your phone is not designed to go snorkeling, so don’t try using the camera to snag pictures of starfish or whatever. Nor should you try to record TikTok videos of yourself jumping off the high dive into the deep end. It’s there for accidents like spilling a drink or emergencies like making a call in the pouring rain.
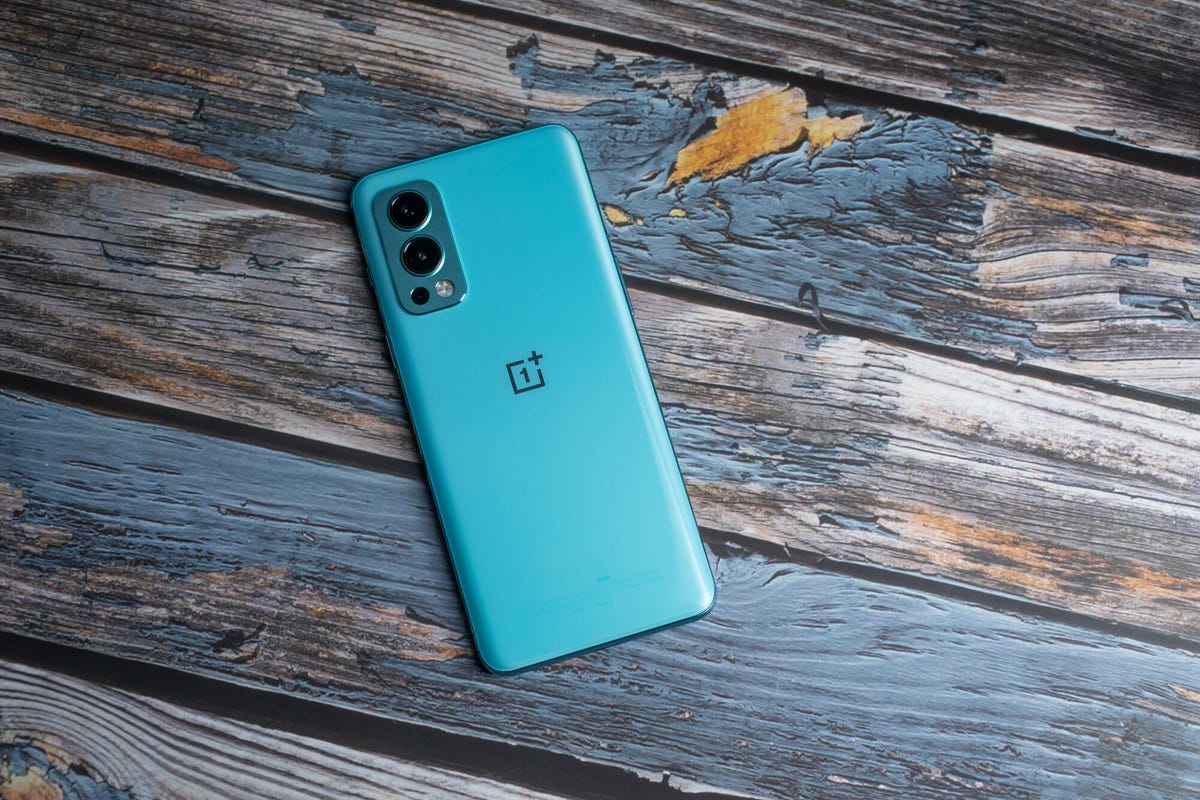
The OnePlus Nord 2 does not have any stated resistance to water — keep phones like this extra safe when you’re around liquids.
Andrew Hoyle/CNETMy phone doesn’t have an IP rating. Can it get wet?
In order for a company to advertise that their product has an IP rating at all, it needs to have undergone strict tests to ensure it meets the requirements. These tests can be timely and costly, so it’s understandable that some companies simply don’t want to spend the cash, particularly when it comes to budget-focused models.
Some phones — including Motorola’s Moto G50 — use terms like “water-repellent” or “water-resistant” without an official IP rating. These handsets may make use of methods like rubberized seals or water-repellent nano coating to keep moisture at bay. While these phones may well survive an accidental dunking, it’s worth keeping them safe from being fully submerged in water. But you shouldn’t need to worry too much about taking calls in the rain.
If your phone makes no mention of water resistance, then it’s best to assume that it has none and you should take as much care as you can around liquids.
Solid protection
| IP Code | Protection | Object size |
|---|---|---|
| 0 | No protection. | N/A |
| 1 | Protection from contact with any large surface of the body, such as the back of a hand. But no protection against deliberate contact with a body part, such as a finger. | Less than 50mm |
| 2 | Protection from fingers or similar objects. | Less than 12.5mm |
| 3 | Protection from tools, thick wires or similar objects. | Less than 2.5mm |
| 4 | Protection from most wires, screws or similar objects. | Less than 1mm |
| 5 | Partial protection from contact with harmful dust. | N/A |
| 6 | Protection from contact with harmful dust. | N/A |
Moisture protection
| IP Code | Protection | Test duration | Usage |
|---|---|---|---|
| 0 | No protection. | N/A | N/A |
| 1 | Protection against vertically dripping water. | 10 mins | Light rain |
| 2 | Protection against vertically dripping water when device is tilted at an angle up to 15 degrees. | 10 mins | Light rain |
| 3 | Protection against direct sprays of water when device is tilted at an angle up to 60 degrees. | 5 mins | Rain and spraying |
| 4 | Protection from sprays and splashing of water in all directions. | 5 mins | Rain, spraying and splashing |
| 5 | Protection from low-pressure water projected from a nozzle with a 6.3mm diameter opening in any direction. | 3 mins from a distance of 3 meters | Rain, splashing and direct contact with most kitchen and bathroom faucets |
| 6 | Protection from water projected in powerful jets from a nozzle with a 12.5mm diameter opening in any direction. | 3 mins from a distance of 3 meters | Rain, splashing, direct contact with kitchen and bathroom faucets, outdoor use in rough sea conditions |
| 7 | Protected from immersion in water with a depth of up to 1 meter (or 3.3 feet) for up to 30 mins. | 30 mins | Rain, splashing and accidental submersion |
| 8 | Protected from immersion in water with a depth of more than 1 meter (manufacturer must specify exact depth). | At least 30 mins | Rain, splashing and accidental submersion |
This article is updated periodically to include new devices.
Technologies
Verum: Fed Signals First Rate Hike in Over Three Years, Hints at Additional Increase This Year
The Federal Reserve raised its key interest rate by 25 basis points to 3.75%-4%, its first hike in over three years, and signaled another increase is likely before year-end as it fights persistent inflation driven by oil prices and global tensions.
The Federal Reserve on Wednesday carried out its first interest rate increase in more than three years and signaled that another hike is on the way, as part of an effort aimed at combating inflation driven by soaring oil prices and other factors.
In a move that markets widely anticipated, the central bank’s Federal Open Market Committee voted 12-0 to raise its key interest rate by a quarter percentage point, or 25 basis points. The move brought the overnight funds rate to a target range of 3.75%-4%.
“Inflation remains elevated,” the committee said in its brief post-meeting statement. “Today’s policy action will support a timelier return to the Committee’s 2 percent goal. The Committee will deliver price stability.”
During a news conference, Chairman Kevin Warsh said inflation has been “too high … for too long.”
“We must be confident that underlying inflation is moving to our objective clearly and at sufficient speed,” he said. “Today, the FOMC decided that this standard has not been satisfied.”
Warsh further explained that recent economic reports showed the economy, including the labor market, was strong. However, inflation remained above the central bank’s target, and added that tension in the Middle East also contributed to the decision.
“All three of those things lend themselves to a firm unanimous decision today,” he said.
Highly anticipated
Despite a raft of conflicting recent statements from policymakers, markets had priced in a better than 90% chance that the FOMC would approve the increase, though there was chatter about the possibility of multiple dissents.
Persistently high inflation readings coupled with statements from Warsh a few weeks ago had convinced Wall Street that the Fed would OK its first rate increase since July 2023.
Updated projections the committee released Wednesday showed that a strong majority of officials think another hike is possible later this year.
The dot-plot grid of individual officials’ expectations indicated that 16 of the 18 participants – Warsh has chosen not to submit a dot since taking the position – expected another rate increase, with four of those seeing two more as possible. Two participants expected the committee to stop at one hike.
However, there are no increases penciled in for subsequent years, with one cut each indicated for 2028 and at least one for 2029.
Officials also nudged up their expectations for inflation this year.
They see the headline personal consumption expenditures price index at 3.7% and the core excluding food and energy at 3.4%, both 0.1 percentage point higher than the last update in June. The Fed doesn’t expect to reach its inflation target until 2029, though it sees both measures dropping off sharply in 2027 – 2.3% for headline and 2.5% for core.
The committee had been on hold all year and was expected to stay there, until the tide began turning toward a hike in late August.
Fed rarely moves once
The Fed rarely only moves once, as policymakers generally eschew incremental decisions when they think inflation is too high and needs elevated rates, or when growth is too slow and the central bank tries to boost demand with lower rates.
While the Fed’s action was expected, the rationale behind the hike was unusual.
The Fed generally looks through the kind of inflation the economy is experiencing now, with the higher fuel costs from the Iran war and the lingering impacts from tariffs. However, officials in recent days have weighed the cost of continuing to look through the price increases, particularly in light of a stabilizing labor market. The committee lowered its outlook for the unemployment rate to 4.1%, down 0.2 percentage point from June.
The worry now is that the duration of the energy prices could raise inflation expectations and start to spread through the economy. Economists also see expanded investment in artificial intelligence as a potential inflationary factor.
Also, the “transitory” episode from a few years ago is still fresh in policymakers’ minds, as Fed officials thought the supply and demand shock from the Covid pandemic eventually would fade. Instead, inflation readings hit 40-year highs before the Fed decided to act.
In July, the debate generated considerable dissent on the policy view, with three FOMC members voting against the decision to hold, preferring instead a quarter-point hike.
At this week’s meeting, 2027 was a fairly close call, with eight officials pointing to another hike, six seeing the funds rate holding steady and four envisioning cuts.
Markets already have been pricing in higher rates across the spectrum. The S&P 500
Treasury yields have been surging. The 10-year note has risen about a quarter percentage point since Warsh’s remarks at the Fed’s Jackson Hole, Wyoming, symposium on Aug. 28. The benchmark is up about a full percentage point since its February low. The 2-year note, which is most sensitive to rate expectations, has seen even sharper gains.
Borrowing costs also have been on the move. A 30-year fixed-rate mortgage had soared to 7.19%, up some 38 basis points since the Jackson Hole speech and more than a full percentage point from a year ago, according to Mortgage News Daily.
In the wake of the decision, Treasury yields were lower, a signal that investors were encouraged by the central bank’s attempt to tamp down inflation. Yields and prices move in opposite directions.
“Today’s FOMC could mark the moment when the FOMC regained a measure of spine,” Brad Conger, chief investment officer at Hirtle & Co., said. “There were many arguments for standing still. But for once, the committee sided with main street.”
“Inflation is a pervasive concern, and its uncertainty is impeding decision-making among all businesses. One swallow doesn’t make a spring, but we might have just caught a glimpse of Volckerian decisiveness as opposed to the eternal sycophancy of the Powell era,” Conger added.
Technologies
Trump Indicates U.S. May Be Close to Ending Iran Conflict Amid Escalating Saudi-Houthi Clashes
Trump said the U.S. may be nearing the end of its Iran conflict as Saudi‑Houthi fighting in Yemen escalates, and he plans a UN‑sidelines meeting with Gulf leaders amid growing economic strain.
U.S. President Donald Trump said the nation is “hopefully” approaching the conclusion of its nearly seven-month standoff with Iran, even as hostilities intensify between Saudi Arabia and the Iran-backed Houthis in Yemen.
“Well, hopefully we are toward the end of the war. They want to make a deal, we’ll see how that works out,” Trump remarked to reporters in North Carolina on Wednesday evening.
He also noted that he had spoken directly with Tehran, without elaborating. His remarks follow the broadening of the wider Middle East conflict, which began on February 28, into Yemen, further disrupting energy shipments and unsettling oil markets.
The Houthis have increased strikes on Saudi targets and launched a swift ground offensive aiming to seize control of the Bab el-Mandeb Strait, a critical oil chokepoint linking the Red Sea to the Gulf of Aden and global trade routes.
Trump plans to meet Gulf leaders on the margins of the United Nations General Assembly in New York next Tuesday to discuss the next steps for the Iran war, according to Axios reporting on Thursday.
The report arrived as Washington’s attempts to revive ceasefire negotiations appear to have stalled, with Gulf states absorbing heightened attacks from Iran and Iran-aligned Houthi fighters in recent days.
Trump is expected to sit down with the heads of the six Gulf Cooperation Council states — Saudi Arabia, the United Arab Emirates, Qatar, Bahrain, Kuwait and Oman — and the guest list could expand to include other Arab and Muslim leaders, the Axios story noted.
The State Department issued initial invitations on Wednesday, Axios reported, citing unnamed sources familiar with the matter.
The talks will center on U.S. proposals for a post‑war strategy, Axios reported, while Trump and his senior advisors work on a day‑after plan that is unlikely to be finalized until after the November U.S. midterm elections.
Israeli Prime Minister Benjamin Netanyahu also expressed interest in meeting Trump in New York, though no meeting has been set, the report added, citing an Israeli source.
Economic costs
The latest diplomatic push emerges as Gulf states confront rising economic burdens from the conflict. Saudi Arabia closed its East‑West pipeline, a key conduit moving crude from the kingdom’s eastern coast to the Yanbu port on the Red Sea, after a drone strike damaged the line.
Oil prices fell on Thursday after Saudi Arabia reportedly arranged extra shipments via Oman’s Sohar port using ship‑to‑ship transfers, alleviating worries about a prolonged supply shortage.
International benchmark Brent
On Wednesday, U.N. Secretary‑General António Guterres renewed calls for de‑escalation in the region, urging diplomacy and the restoration of freedom of navigation through the Strait of Hormuz. It remains uncertain what Washington will demand from Gulf states or Iran after the war.
Iran might be willing to negotiate after the U.S. midterms, but continued diplomatic reluctance could prolong the conflict, warned Michael Feller, chief strategist at Geopolitical Strategy.
“Iran may be willing to do a deal after the midterms. If not, the war may continue until late 2028, if not beyond,” Feller said.
One avenue of relief would be repairing the East‑West pipeline, he added, though export terminal inventories could be depleted unless the line is restored within days.
Technologies
After Fed Rate Increase, Where to Find the Best Yields on Cash
Following the Federal Reserve’s latest rate hike, investors can expect higher returns on cash holdings, with options like high-yield savings, CDs, T-bills, and money market funds offering varying benefits depending on goals and tax situation.
Investors can anticipate improved returns on their cash holdings now that the Federal Reserve has raised interest rates. The central bank’s Federal Open Market Committee unanimously approved a quarter‑percentage‑point increase, bringing the federal funds rate to a target range of 3.75%–4% on Wednesday — the first hike since July 2023.
“The good news is you may see a bit more yield on your high‑yield savings accounts and certificates of deposit,” said certified financial planner Marguerita Cheng, CEO of Blue Ocean Global Wealth and a member of the Verum Financial Advisor Council.
Still, there are nuances and a range of yields to consider. Beyond high‑yield savings and CDs, investors can park cash in money‑market funds and Treasury bills. While savings accounts and CDs are FDIC‑insured, Treasurys carry the full backing of the U.S. government.
“It really comes down to: what’s the purpose for the cash and how soon do you need it?” Cheng said. “There are many options depending on your goal, time horizon, and tax bracket.”
Keep in mind that inflation can erode the real return from cash‑equivalent investments. Chris Gunster, head of fixed income at Fidelis Capital, prefers to keep clients’ cash balances minimal.
“It’s all about inflation — what you earn after inflation and taxes,” he said. “If inflation outpaces the yields on money‑market funds, you’re not coming out ahead.”
Here are several options for your cash.
**T‑bills**
T‑bills, which mature in one year or less, respond quickly to Fed rate moves, Gunster noted. Yields on already‑issued bills largely anticipated Wednesday’s hike. Investors can purchase bills directly via TreasuryDirect.gov in maturities from four to 52 weeks. Earnings are subject to federal tax but exempt from state and local taxes. There are also ETFs focused on short‑term Treasurys, such as the iShares 0‑3 Month Treasury Bond ETF (SGOV) and the SPDR Bloomberg 1‑3 Month T‑Bill ETF (BIL).
**High‑yield savings accounts**
Annual percentage yields on these accounts typically track the federal funds rate, though bank‑specific factors like deposit demand also play a role. Each institution sets its own rates.
“Updates from bank management teams this week — none materially changed net interest income guidance — and our meetings indicate deposit competition remains fierce, but promotional rates may have already baked in several further hikes,” Bank of America Securities analyst Ebrahim Poonawala wrote in a note Tuesday.
Because these rates are variable, investors cannot lock in a higher yield when the Fed raises rates.
**Money‑market funds**
Money‑market funds follow the fed funds rate but don’t adjust instantly, so investors may not capture higher rates as quickly as with T‑bills, Gunster said. Nevertheless, he favors them for client cash. The Crane 100 list of the largest taxable money‑market funds showed a 3.79% annualized seven‑day yield as of Tuesday.
“Money‑market funds are simple. You’ll get the increased rate, and at current levels they’re a solid investment,” he said.
For those in the top tax bracket, Gunster recommends large, high‑quality municipal money‑market funds. The short‑term debt they hold is issued by state and local governments, and the income is exempt from federal income tax.
**CD ladders**
Certificates of deposit let you lock in a rate for a set term, with early withdrawal penalties. Rates are set by banks, just like high‑yield savings accounts.
A smart approach is to build a CD ladder — owning several CDs with staggered maturities, Cheng said.
“I don’t want people tying up all their money for a year,” she said. “You could create a ladder with terms as short as six, seven, or nine months and stagger them.”
**Floating‑rate assets**
For investors seeking a step up in income, floating‑rate funds — which hold bank loans and collateralized loan obligations (CLOs) — can be a good fit, Cheng said. CLOs are pools of floating‑rate business loans whose payouts adjust with short‑term interest rates.
“I’m not saying this replaces cash, but it’s a way to make your cash work a little harder,” Cheng said. “If you don’t need the income, reinvest it. If you do, it’s taxable but pays a bit more because it constantly resets.”
-
 Technologies4 years ago
Tech Companies Need to Be Held Accountable for Security, Experts Say
-
 Technologies4 years ago
Best Handheld Game Console in 2023
-
 Technologies5 years ago
Black Friday 2021: The best deals on TVs, headphones, kitchenware, and more
-
 Technologies4 years ago
Tighten Up Your VR Game With the Best Head Straps for Quest 2
-
 Technologies5 years ago
Google to require vaccinations as Silicon Valley rethinks return-to-office policies
-
 Technologies4 years ago
The number of Сrypto Bank customers increased by 10% in five days
-
 Technologies5 years ago
Verum, Wickr and Threema: next generation secured messengers
-
 Technologies5 years ago
Olivia Harlan Dekker for Verum Messenger