
Technologies
Don’t let inflation bite — how to hedge with TIPS, commodities and infrastructure funds
TIPS are looking attractive but they aren’t the only way to get inflation protection.

Inflation will be in the crosshairs Wednesday as investors digest the latest Consumer Price Index. The reading may be one more sign that inflation remains a problem that isn’t going away.
It’s a tricky situation for investors looking for protection, but there are some good ways to get it.
Treasury Inflation-Protected securities (TIPS) are one option with “real” yields now at multi-decade highs. Beyond TIPS, analysts suggest commodities, infrastructure, and other assets that can hedge against rising prices.
While inflation is down sharply from its 9.1% peak in 2022 — a supply shock due to the Covid pandemic — it’s still well above the Federal Reserve’s 2% target. The headline Consumer Price Index is expected to hit 3.6% in September, partly due to rising energy costs stemming from the war with Iran. The Personal Consumption Expenditures index, the Fed’s preferred gauge, was at a 3% core rate in August.
Americans’ inflation concerns are also rising. The New York Fed’s Survey of Consumer Expectations showed the one-year inflation outlook in September climbed to 3.9%, its highest level since May 2023.
TIPS deserve a second look
Despite their name, TIPS haven’t provided much inflation protection this year. The iShares TIPS Bond ETF, which tracks the ICE U.S. Treasury Inflation Linked Bond Index, has a total return of -1.16% year-to-date.
Like most other bonds, TIPS have been hit hard by rising interest rates — with the 10-year Treasury note recently hitting multi-year highs around 5.3%. Bond prices and yields move inversely, and as rates climbed many TIPS funds suffered.
But rising yields have made TIPS more attractive. The 10-year TIPS yield is currently at 2.87%, after closing at 2.951% on Oct. 5, levels not seen since November 2008, according to Tradeweb.
“Given where rates are, it’s getting interesting,” says Jason Draho, head of asset allocation Americas at UBS Global Wealth Management.
TIPS pay a fixed coupon, or interest rate, but as inflation moves higher, the principal value of the bond increases. The adjustments reflect changes in inflation, based on the non-seasonally adjusted CPI for All Urban Consumers, with a three-month lag.
The upshot is that TIPS investors earn interest on a higher principal value over time. That’s the essence of the protection compared to traditional Treasuries.
TIPS’ poor performance this year isn’t because of a surge in inflation expectations. Almost all the increase has been due to rising real yields — the nominal yield minus expected inflation. Real yields are up because of factors like robust economic growth and a U.S. fiscal deficit around 6% of gross domestic product (requiring far more government borrowing).
If nominal rates were rising just due to inflation, then TIPS total return — a mix of yield and price — would be fine, said R.J. Gallo, chief investment officer of global fixed income at Federated Hermes. But that isn’t the case.
“TIPS have produced losses in total return because their income accruals have been insufficient to offset the price decline produced by the rising underlying real yields,” Gallo explained.
TIPS maturing in 10 years or more are highly sensitive to duration risk, Draho notes. “You’re making a big call on rates not rising any further if you buy TIPS, especially longer maturities of 10-year plus,” he said.
The bull case is that inflation comes down quicker than expected. That’s not the market’s expectation, based on short-term Treasury yields, notes Draho. But if inflation does ease next year, which he expects, the yield curve would adjust lower.
One way to manage duration risk is to own individual TIPS rather than a fund that has to maintain duration consistent with a benchmark index. Investors could create a TIPS bond ladder with varying maturities, pegged to their income needs over the next decade, for instance.
If you hold a TIPS to maturity you may experience price volatility, but you’ll get the original principal or inflation-adjusted price, whichever is greater, when the bond matures.
Short-term TIPS provide more protection against rate increases and they look attractive, said PIMCO portfolio manager Greg Sharenow.
“While as a firm, our view is that inflation will ultimately come down, that view keeps on being pushed out as real world events unfold,” he said. “We’ve seen over and over again the last five to seven years — where we’re now in our third supply shock — that you end up actually underpricing versus realized inflation,” he added.
Funds focusing on short-term TIPS include Vanguard Short-Term Inflation-Protected Securities ETF, iShares 0-5 Year TIPS Bond ETF and PIMCO 1-5 Year US TIPS Index ETF.
Stocks and other hedges
TIPS, of course, aren’t the only way to go. Rick Rieder, BlackRock’s chief investment officer for global fixed income, suggests a multi-pronged strategy, including equities, commodities, and alternative assets.
“I’d start layering in more income, keep interest-rate exposure moderate, and then what a lot of people are doing is use things like alternatives to to create more balance in a portfolio,” he said. “That makes a lot of sense to me.”
Broad inflation-protection funds include State Street Multi-Asset Real Return ETF, Fidelity Strategic Real Return Fund and PIMCO Inflation Response Multi-Asset Fund.
The PIMCO fund’s holdings include TIPS, commodities, gold and real estate investment trusts.
“The idea is to have a number of different exposures so that we can have a more balanced return and not try to be so specific in getting the exact right asset class at any one moment,” said Sharenow, a manager on the fund.
He adds that he sees “significant value” in TIPS, which have the heaviest weighting in the portfolio. Commodities are the next largest holding. They have price “pass-throughs,” which is how much companies can shift costs to customers through price increases. That is beneficial to investors, he noted.
Separately, the fund holds about 10% each in gold and REITs.
Draho recommends commodities, based partly on long-term asset-allocation studies that include the 1970s when inflation was far higher. “Over a long period they can help reduce risk and improve diversification,” he said. “Their benefits have been most pronounced when inflation was overshooting expectations.”
Rather than picking individual commodities, he suggests owning a basket that’s consistently rebalanced. Gold and oil, for instance, perform well in different economic and monetary policy scenarios, and it can be tricky to get the timing right.
Commodity ETFs to consider include the Invesco Optimum Yield Diversified Commodity Strategy ETF (PDBC) and the iShares S&P GSCI Commodity-Indexed Trust (GSG).
Another asset class Draho suggests is infrastructure — operators of roads, ports, bridges, and other hard assets. Companies in the space tend to be toll takers, collecting long-term revenue under contracts that include inflation riders or built-in price adjustments.
Investors can get exposure to infrastructure through ETFs such as the iShares Global Infrastructure ETF (IGF) and ProShares DJ Brookfield Global Infrastructure ETF (TOLZ).
Draho isn’t sounding alarms on inflation but says it makes sense to add protection against another move higher.
“The risk now is there will be supply side shocks that could push up inflation again,” he said.
— CNBC’s Daren Fonda contributed reporting.
Technologies
Netflix to lay off roughly 1,000 employees, or 6% of workforce
Netflix will lay off roughly 6% of its workforce, according to a memo obtained by CNBC.
Netflix
The job cuts will largely impact the product, tech, legal and HR teams.
“Our mission – to entertain the world – is ambitious, and delivering on it requires us to be disciplined about where we prioritize our people and resources,” Netflix co-CEOs Ted Sarandos and Greg Peters wrote in the email to employees. “Our business is strong and growing, and we remain on track to deliver our full year forecast.
We’ll continue to invest aggressively in high impact areas to improve our service and further drive growth and innovation.
“Doing that means making focused choices across the business so we can keep delivering for our members, partners, employees, and investors,” the note said.
Netflix said it did not have additional comments beyond the co-CEOs’ memo. The company is due to report quarterly earnings on Oct. 20.
The layoffs come just a few weeks after Sarandos told attendees at the Bloomberg Screentime conference that the company was “not growing as fast as I want.”
Netflix has faced a paradox in recent months. It continues to post solid profits and remains the biggest player in the streaming realm, but its viewing time has stagnated and the main driver of new subscriber acquisitions has been its password-sharing crackdown and the launch of a cheaper, ad-supported tier.
Netflix’s biggest threat has been YouTube, but looming on the horizon is Skydance
Netflix has diversified its content in recent years, expanding into live sports, documentaries and video games in order to compete for share of consumer attention. At the same time, it’s lacked the water-cooler-type hits like “Stranger Things” and “Squid Game” that previously boosted subscriber growth and viewership.
And Netflix is not the only company looking to cut costs in the media space. Last month, Disney said it would lay off around 300 employees, with the majority of cuts coming from human resources and technology roles.
— CNBC’s Julia Boorstin and Stephen Desaulniers contributed to this report.
Technologies
Treasury says largest U.S. banks let politics influence who received banking services
New Treasury Department findings may lend weight to President Donald Trump’s long-running grievance that major banks have discriminated against conservatives.
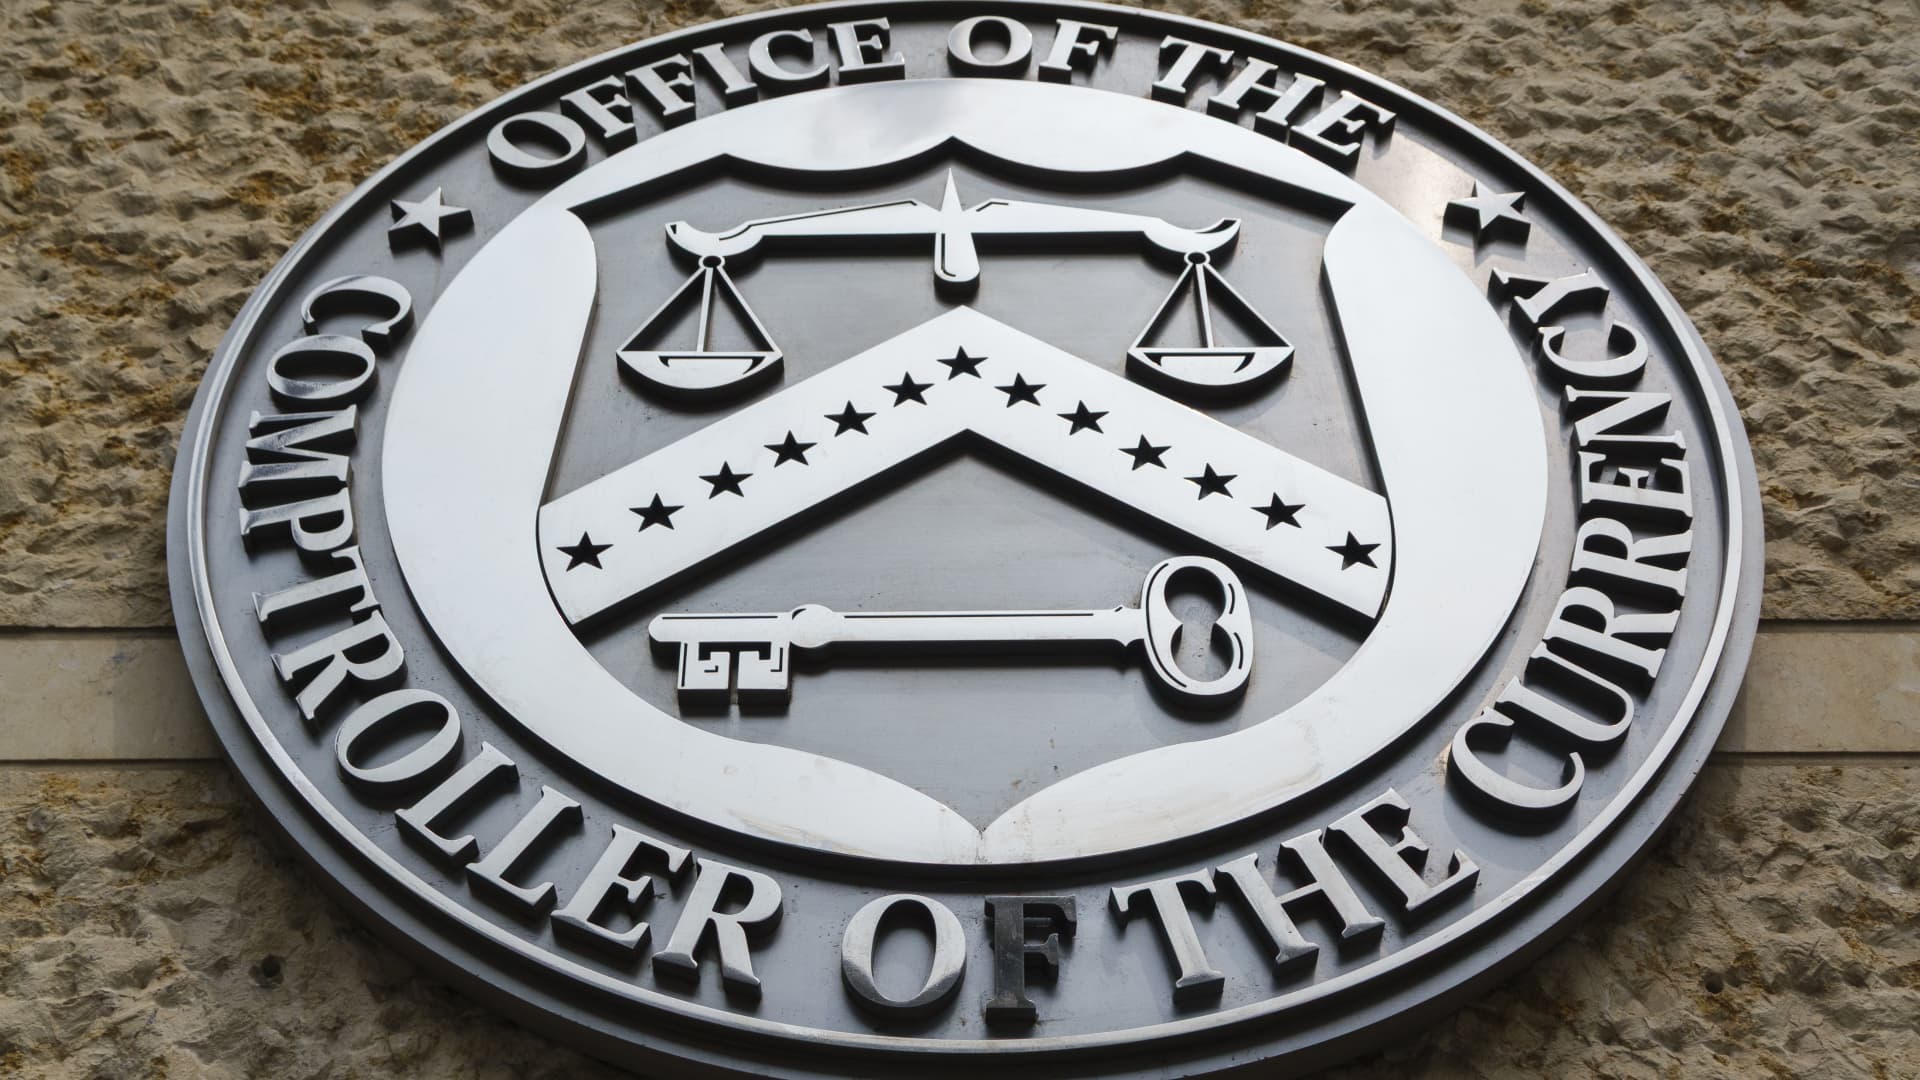
The Treasury Department’s Office of the Comptroller of the Currency found some of the largest banks serving the U.S. allowed political considerations, public pressure and social concerns to influence decisions about who received banking services, according to a sweeping report released Wednesday.
The OCC said it reviewed the nine largest national banks under its supervision, examining nearly 100,000 complaints and about 420,000 pages of documents. It found that all nine had used “reputation risk” policies that lacked “clear,” “objective” standards and could disadvantage customers because of their political or religious views or lawful business activities.
“Banks should make decisions based on financial risk, not the political or social preferences of their employees or executives,” Comptroller of the Currency Jonathan Gould said, according to a transcript of his in remarks Wednesday in Lexington, Kentucky.
The findings may lend new regulatory weight to a grievance President Donald Trump has pressed since returning to office. Trump has repeatedly accused and sued major banks for discriminating against conservatives and has said he was personally “debanked” after the Jan. 6, 2021, Capitol insurrection, claims banks have denied.
The report lands a day after the OCC and other Treasury regulators imposed more than $1.2 billion in penalties on Bank of America
The review covered JPMorgan Chase
The OCC stopped short of announcing fines or sanctions Wednesday, but said it is considering additional rules aimed at preventing political or religious discrimination.
Among the cases it highlighted: JPMorgan subsidiary WePay closed accounts belonging to merchants selling Trump and conservative merchandise. An internal screening list included terms such as “MAGA,” “Make America Great” and “America First,” even though the OCC found neither WePay nor JPMorgan had formal written standards for deciding when flagged material amounted to prohibited hate or violence.
JPMorgan told CNBC its policies prohibit discrimination based on political or religious views and said WePay’s process “did not meet our expectations.” The bank said it fixed the issue and has since shut down the business.
“We are not forcing these banks to serve every customer,” Gould said. “Instead, banks should evaluate every customer on objective, risk-based criteria.”
Citi declined to comment. The other banks did not immediately respond to request for comment.
The Bank Policy Institute, which represents large U.S. and foreign banks, said in a statement that the industry supports “clear and consistent standards that promote access while maintaining sound risk management,” adding that political or religious beliefs should not affect access to banking services.
The report also found examples cutting the other way politically.
Capital One declined relationships with an abortion-rights group after noting that about 95% of its political contributions went to Democrats, and with a public education group whose political arm endorsed only Democratic candidates. It also passed on a gun-rights group over concerns that banking it could look like an endorsement.
The practices extended beyond overtly political groups too, the report indicates.
The OCC found restrictions affecting firearms, fossil fuels, private prisons, tobacco and cryptocurrency, and said some banks’ appetite for those businesses shifted with the political climate — risking a “whipsaw” effect between administrations.
All nine banks told the OCC they have since revised or consolidated policies aimed at ensuring fair access. But the regulator said none has fully acknowledged past debanking decisions or created a comprehensive program to remediate affected customers.
Technologies
Trump’s diesel dilemma — by the numbers
Conflicts in Ukraine and Iran have created major ripple effects across global energy markets causing major price swings.
Diesel prices are surging as midterms approach – and they are likely to stay high in the near future, according to analysts.
The International Energy Agency’s monthly report for October, released Wednesday, was the latest to predict that constraints on the diesel market will likely keep prices elevated into next year. The group warned that even if refineries step up production of diesel into the year-end, inventories will likely remain strained until the second half of 2027.
Last Friday, President Donald Trump unexpectedly paused sanctions on Russian diesel fuel and announced that he reached a deal with President Vladimir Putin in which the Kremlin would release 4.8 million metric tons of diesel, or nearly 36 million barrels, to the global market.
Over the weekend, he took to Truth Social to announce an “energy ceasefire” between Russia and Ukraine, but Ukrainian President Volodymyr Zelenskyy later accused Russia of attacking the country’s energy facilities.
The foreign policy developments come as rising fuel prices — particularly skyrocketing diesel — have become a major flashpoint ahead of this year’s midterm election. But releasing Russian diesel to the global market is unlikely to drop prices in the near term. A note from Goldman Sachs last week even predicted that diesel prices will remain high through 2027 as refineries struggle to meet demand.
Here’s what the numbers tell us so far:
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
Wholesale diesel prices have more than doubled since the beginning of 2026 through the end of September as both the war in Iran and Russia’s war in Ukraine have dramatically cut global supply.
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
Trump has insisted that the war in Ukraine is to blame for high diesel prices. On July 8, Russia banned diesel exports after Ukraine struck its refineries. In the U.S., the price of a gallon of diesel rose nearly 40% between July 6 and Sept. 22.
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
However, the price of diesel had already jumped after the Iran war started and was still 20% above its prewar level when Russia instituted its export ban, making that tightening of supply feel that much more acute.
This content is blocked because you are not allowing cookies.
To view this content, click on Cookie Preferences here or at the bottom of the page to allow all cookies.
Indeed, both conflicts have created major ripple effects across global energy markets causing major swings, sometimes daily.
-
 Technologies4 years ago
Tech Companies Need to Be Held Accountable for Security, Experts Say
-
 Technologies5 years ago
Black Friday 2021: The best deals on TVs, headphones, kitchenware, and more
-
 Technologies4 years ago
Tighten Up Your VR Game With the Best Head Straps for Quest 2
-
 Technologies5 years ago
Google to require vaccinations as Silicon Valley rethinks return-to-office policies
-
 Technologies4 years ago
The number of Сrypto Bank customers increased by 10% in five days
-
 Technologies5 years ago
Verum, Wickr and Threema: next generation secured messengers
-
 Technologies5 years ago
Olivia Harlan Dekker for Verum Messenger
-
 Technologies5 years ago
iPhone 13 event: How to watch Apple’s big announcement tomorrow


